

Welcome to “Stock of the Week”, a recurring series focused on companies experiencing meaningful news flow or changes in their investment case. The objective is not to react to headlines but to understand what is happening beneath the surface and whether recent developments materially affect the long-term investment thesis.
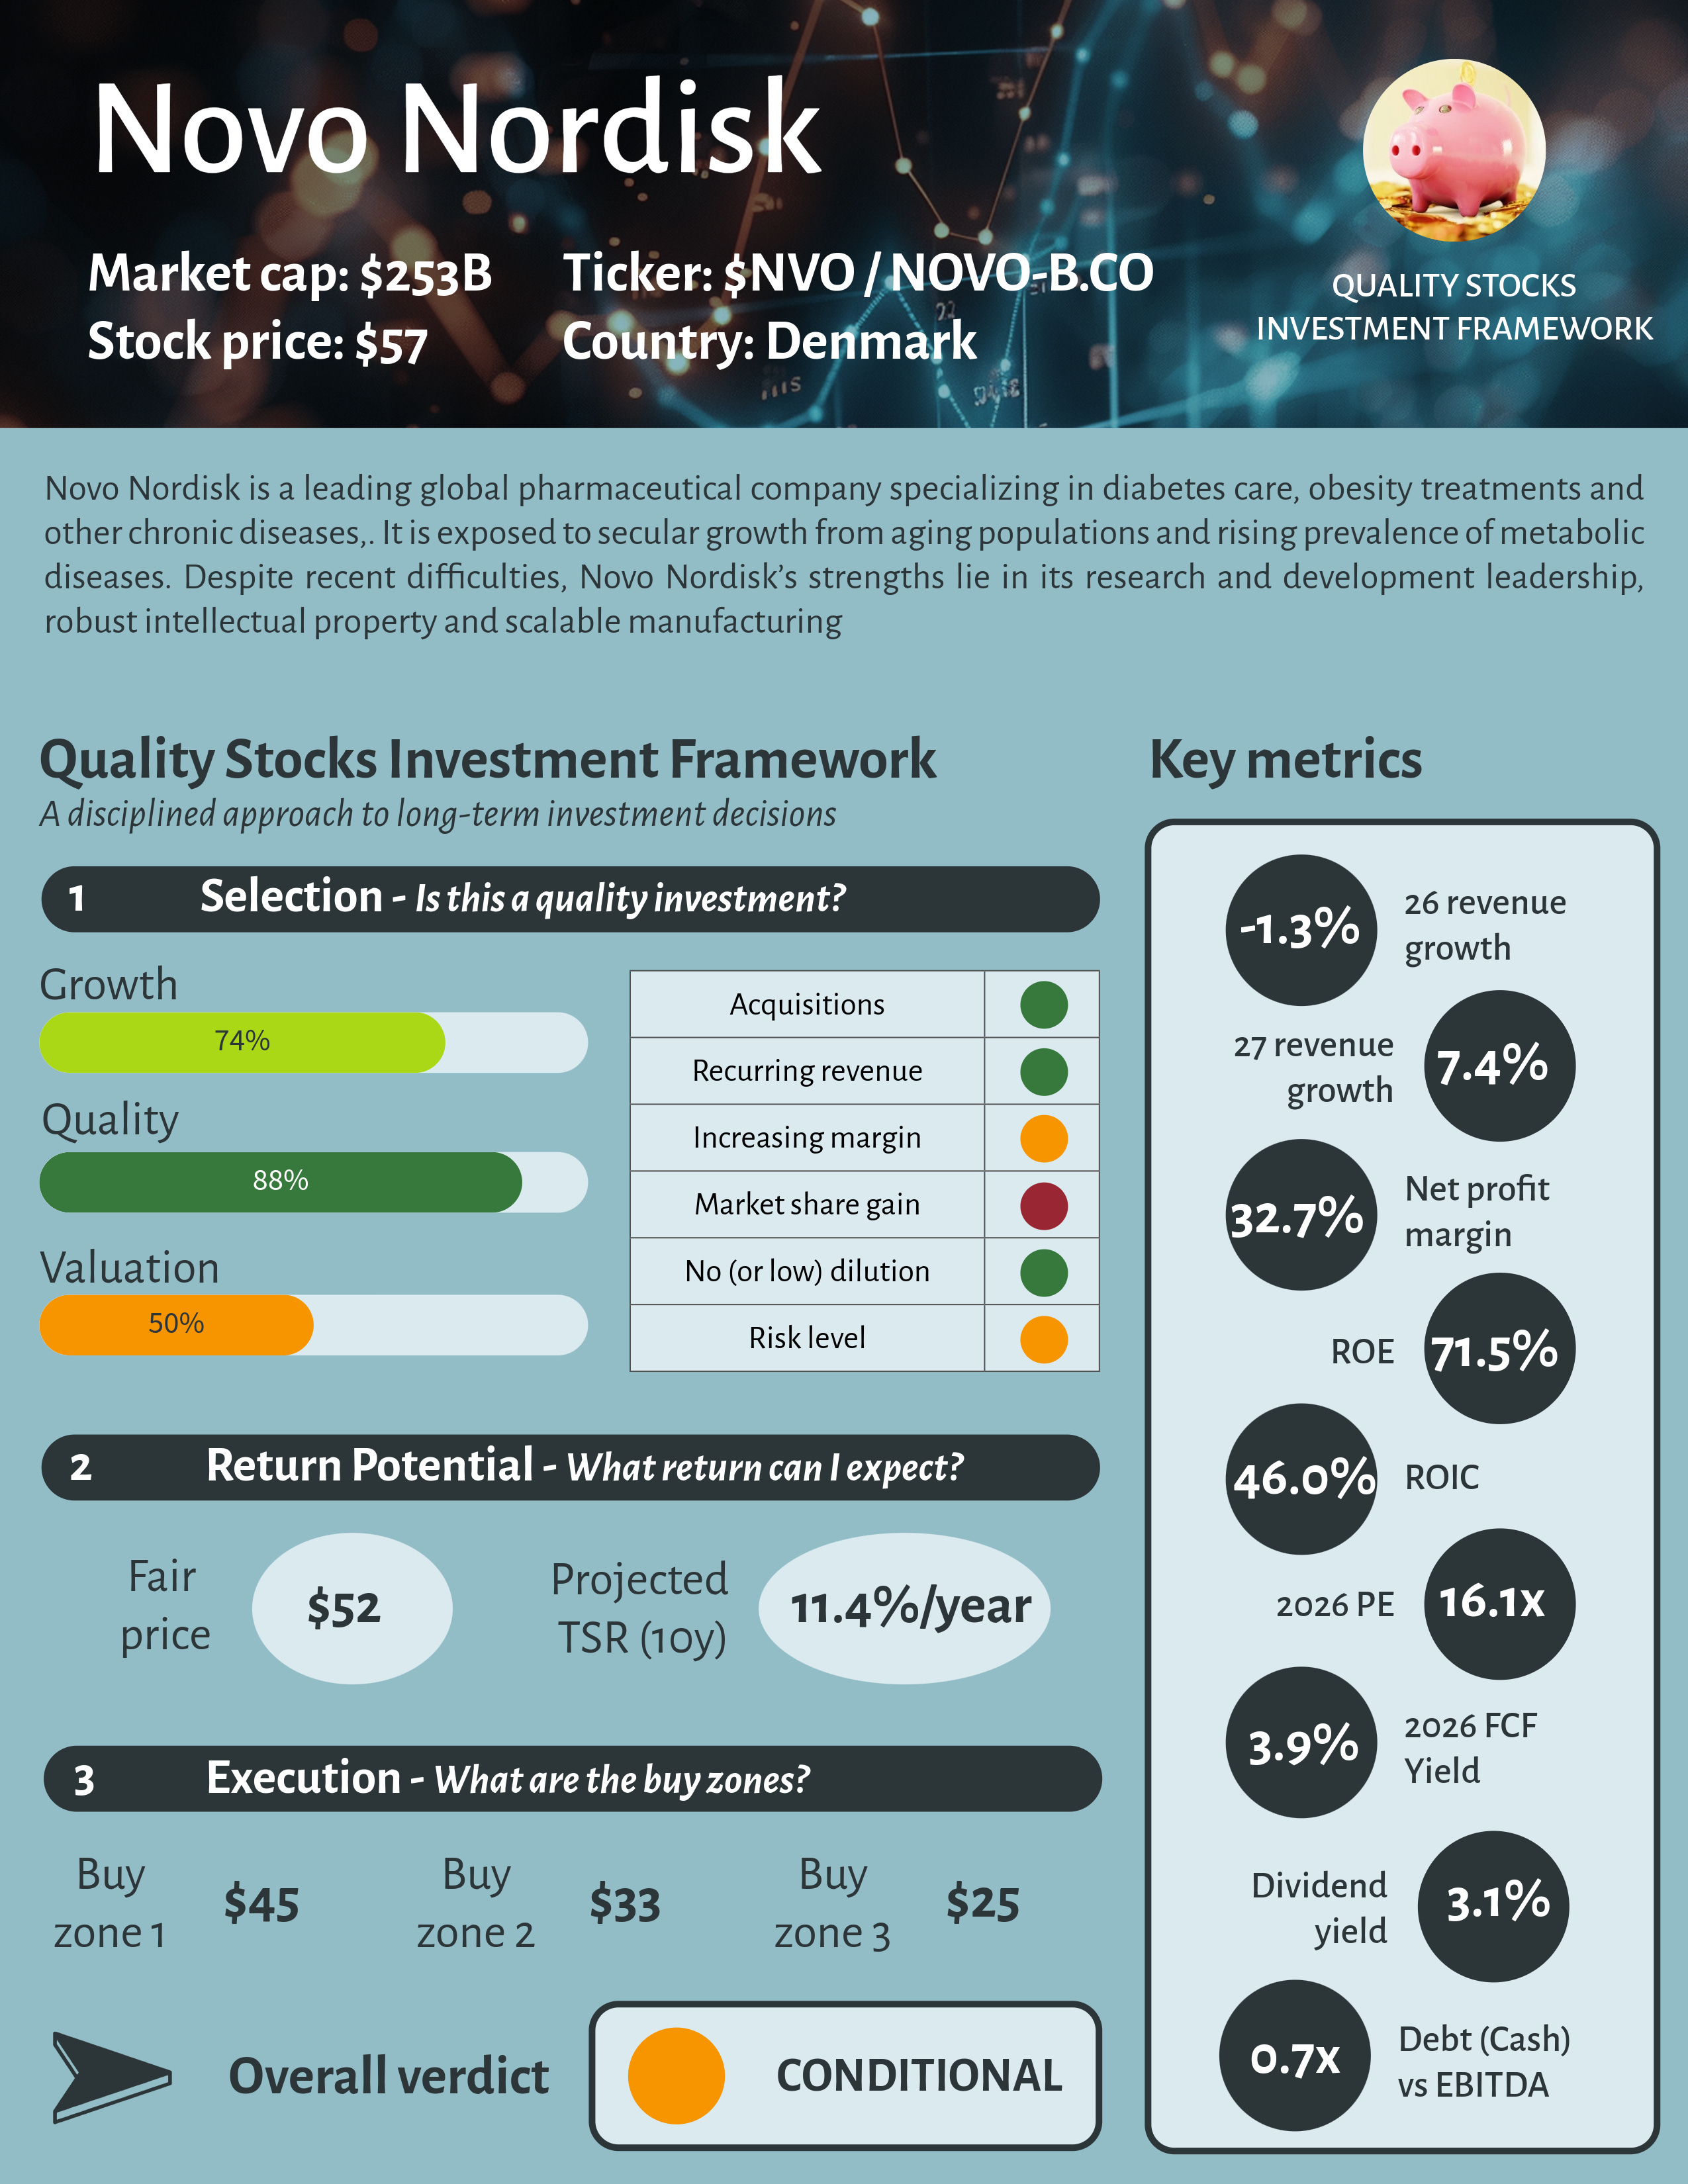
Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and execution, in order to determine whether the stock is Attractive, Conditional, or Unattractive at the current price. A standardized one-pager accompanies each edition to make the decision process clear and easy to follow.
For paid subscribers, Stock of the Week goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
For this week’s edition, the focus is on Novo Nordisk, the Danish pharmaceutical giant, where an improving newsflow and renewed momentum in oral therapies could mark a potential inflection point for the stock.
Last Week’s Stock of the Week

One Pager
The stock at a glance
Recent news
The explosion in demand for GLP-1 is driven by the global obesity epidemic and the proven efficacy of these therapies in achieving substantial weight loss (15% - 20% on average), reducing cardiovascular risks and managing type 2 diabetes
Semaglutide-based treatments like Ozempic and Wegovy have transformed obesity from a lifestyle issue into a treatable chronic disease, creating a strong patient and physician adoption
Novo Nordisk launched the first oral GLP-1 for obesity (the Wegovy pill). This needle-free option addresses patient preference barriers and expands access, with manufacturing investments ensuring no repeat of prior shortages that previously limited growth and allowed compounded copies to erode sales
The company faced headwinds in 2025, including slowing growth (multiple guidance cuts amid US pricing pressures and competition especially with Eli Lilly), but entered 2026 with tailwinds: aggressive price reductions (up to 70% for cash-pay and negotiated channels), the oral Wegovy launch positioned for clean supply and volume upside
GLP-1 supply constraints have largely eased due to massive capacity expansions by both leaders, while demand continues to accelerate with oral formats, broader indications (cardiovascular, …) and improving reimbursement. The overall market is projected to grow robustly
These dynamics position suppliers like Novo Nordisk for renewed volume-driven growth in 2026, offsetting (at least partially) pricing pressures
The CEO is betting on an offensive strategy from ramping up production, launching new produtcs (higher dose formulation, new usages). The company expects a difficult year in 2026 but remains positive for its long-term growth outlook
Recent analyst recommendation updates
January, 07. Barclays. Hold. 375DKK —> 360DKK
December, 16. DNB Carnegie. Buy. 445DKK —> 440DKK
December, 15. Kepler Chevreux. Buy. 510DKK —> 430DKK
December, 09. HSBC. Hold. 300DKK —> 350DKK
Decembre, 08. JP Morgan. Buy. 500DKK —> 350DKK
To go beyond the initial assessment, paid subscribers unlock the detailed TSR calculation with underlying assumptions and my analysis of the situation, providing deeper insight into how recent developments affect risks, opportunities and the overall verdict.
