

Welcome to “Stock of the Week”, a recurring series focused on companies experiencing meaningful news flow or changes in their investment case. The objective is not to react to headlines but to understand what is happening beneath the surface and whether recent developments materially affect the long-term investment thesis.
Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and execution, in order to determine whether the stock is Attractive, Conditional, or Unattractive at the current price. Please note that is not financial advice. A standardized one-pager accompanies each edition to make the decision process clear and easy to follow.
For paid subscribers, Stock of the Week goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
This week’s spotlight is on BNP Paribas, which has just released its Q2 and first-half 2026 financial results. While banks are often seen as “boring stocks” and receive less attention than trendy growth companies, they remain highly attractive for income investors who are not afraid of a bit of cyclicality. As the Eurozone's largest bank, all eyes have been on its ability to navigate the tail-end of the central bank rate-cutting cycle while executing its strategy. We will run BNP's updated numbers through our Quality Stocks Investment Framework to see if its accelerating market share gains and operating leverage translate into a compelling long-term thesis.
Missed an edition? Catch up on our recent analyses


One Pager
The stock at a glance
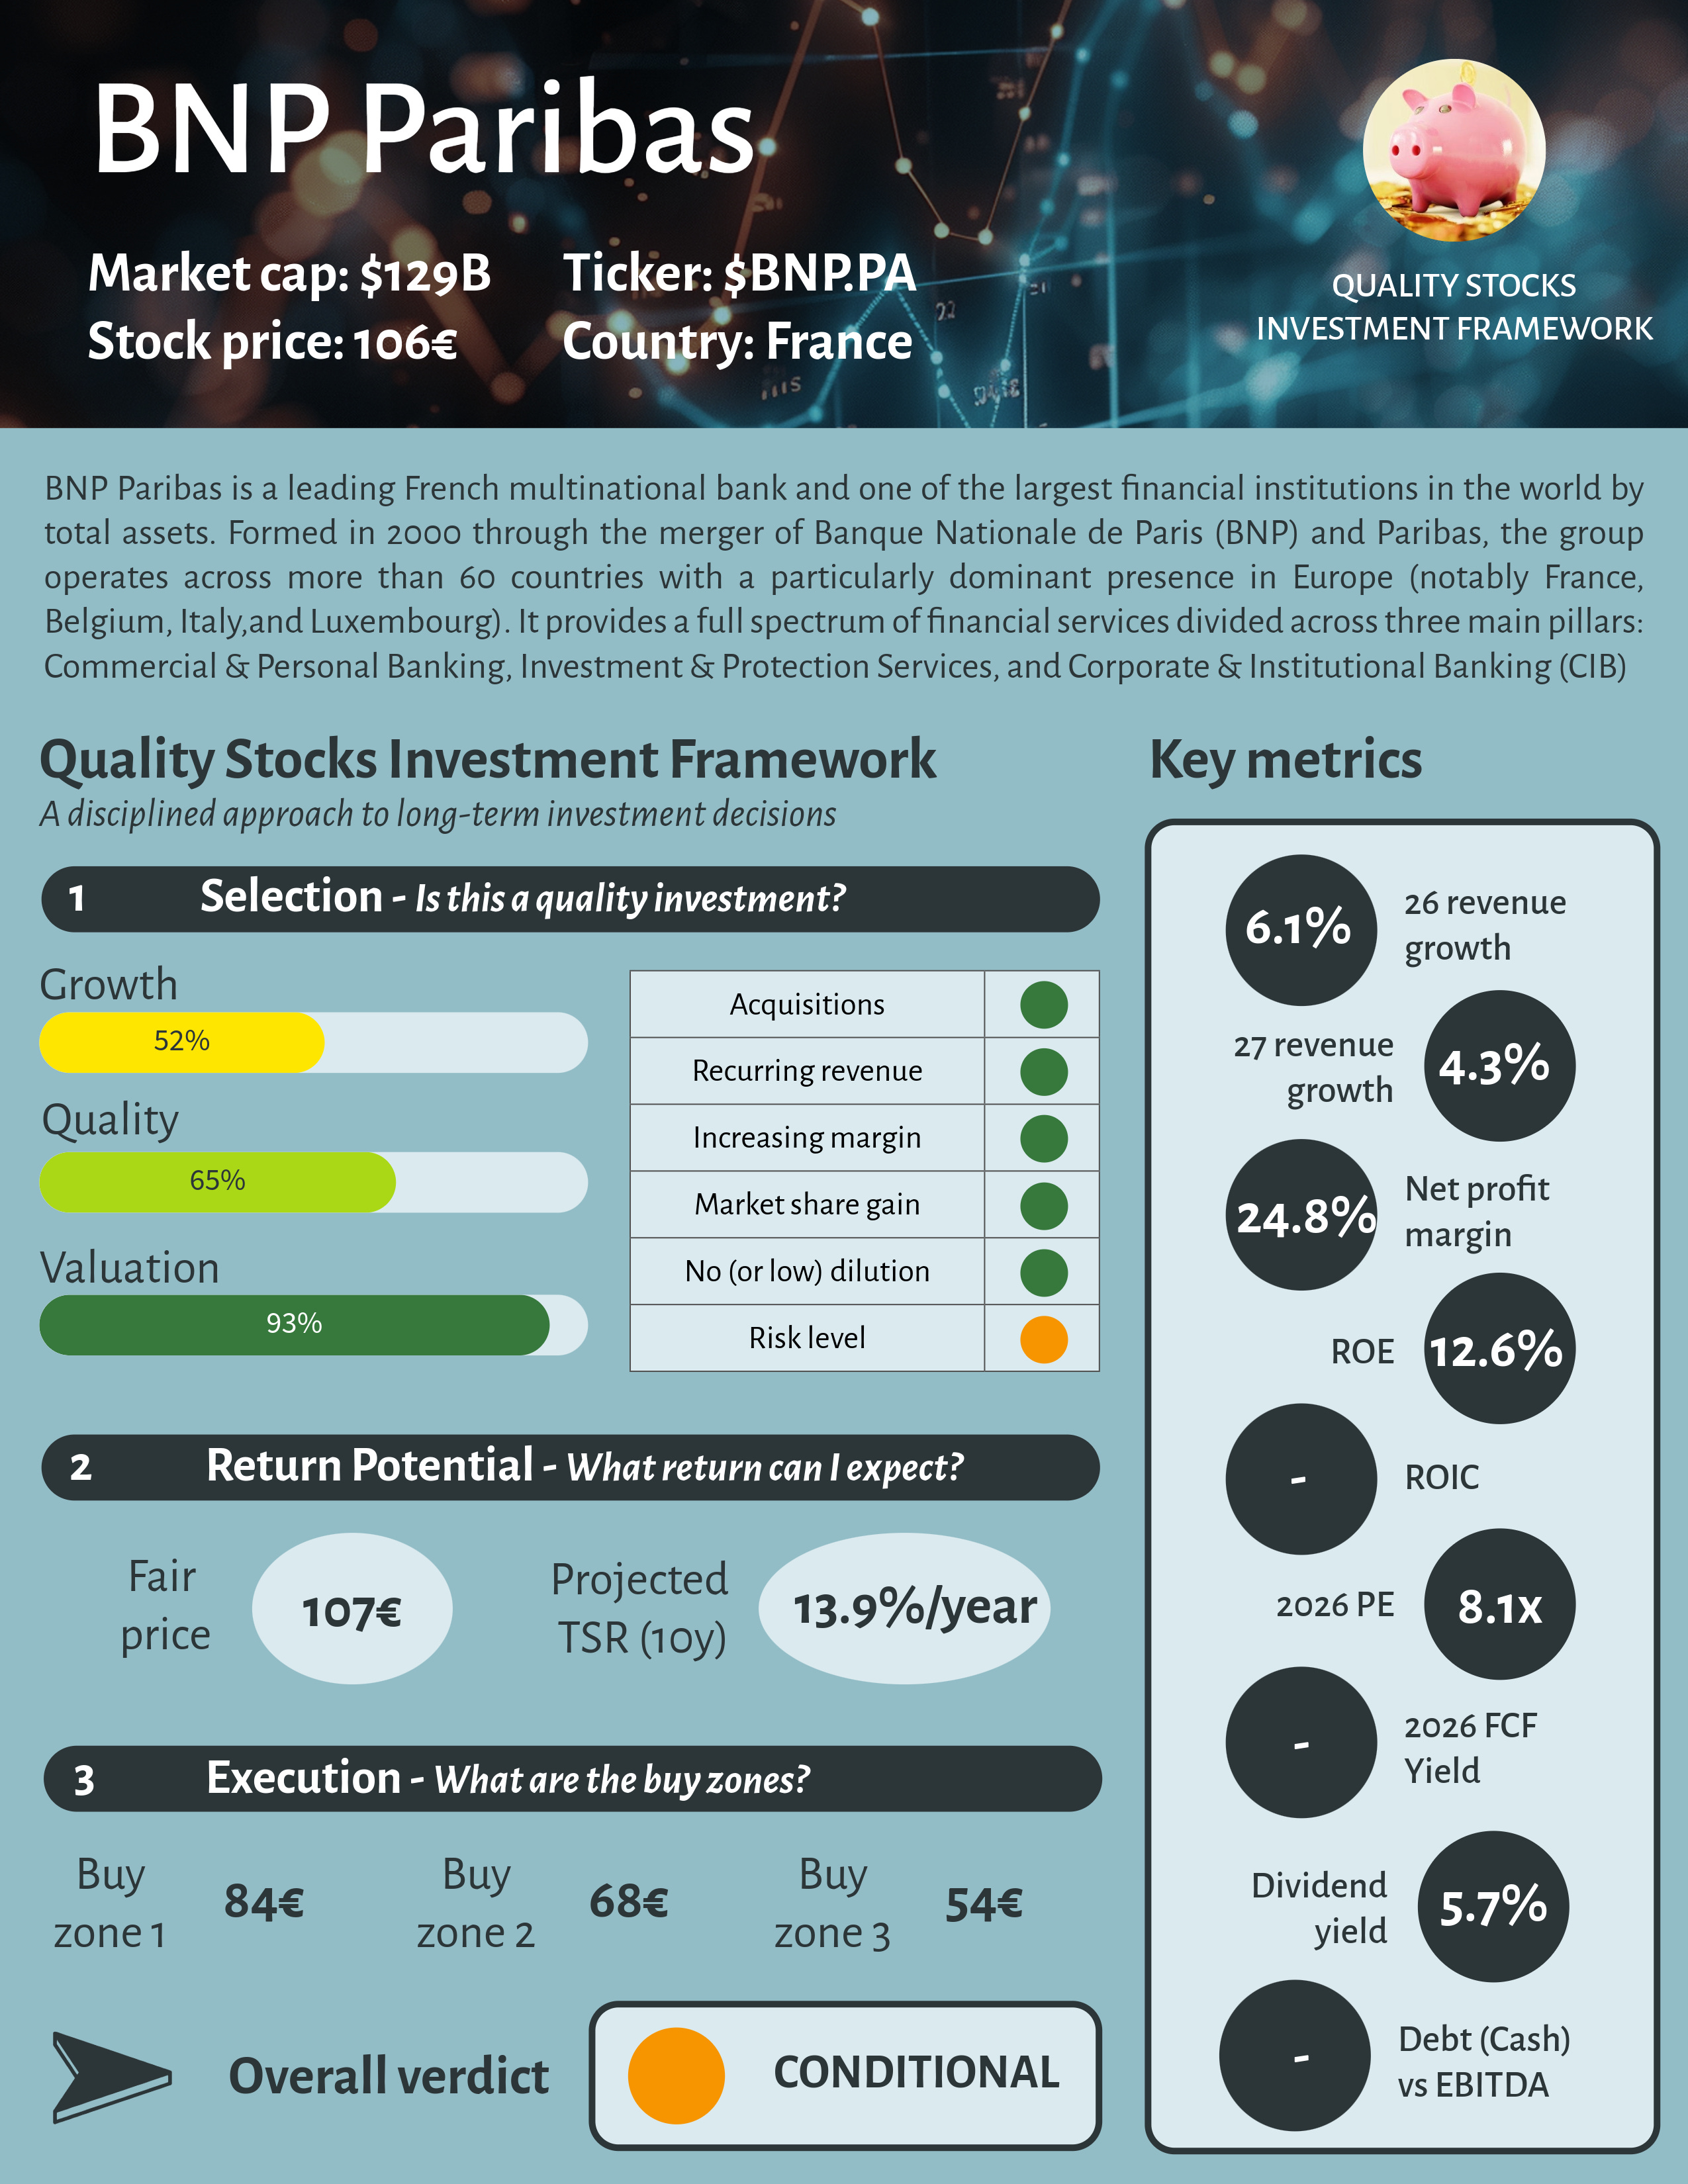
Want to understand how the Quality Stocks Investment Framework works? This article breaks it down for you

Data for this week’s analysis was sourced via MarketScreener. It is my go-to platform for global stock data and analyst price targets. If you are looking to upgrade your research toolkit, click here (Full disclosure: this is an affiliate link, so you will be supporting this newsletter at no extra cost to you!)
Recent news
The group executed a strategic pivot in its asset management strategy by finalizing the operational creation of a single unified entity integrated with AXA Investment Managers, establishing a European powerhouse with over 1.6T€ in assets under management
In a consolidation move, the bank expanded its market dominance by closing long-term institutional agreements, including a major structural partnership with Ageas and the divestment of its BMCI stake in Morocco to optimize its capital structure
The long-term financial outlook is to compound an annual net income growth rate above 10% through 2028, a strong cost-to-income efficiency target below 56% and a Return on Tangible Equity (RoTE) consistently exceeding 13%
Global client engagement metrics reached an all-time high as the corporate banking arm aggressively expands its regional pipeline, highlighted by its Global Markets equity and prime services division
Latest results
In a macroeconomic climate marked by shifting central bank rates and market volatility, BNP delivered robust results.
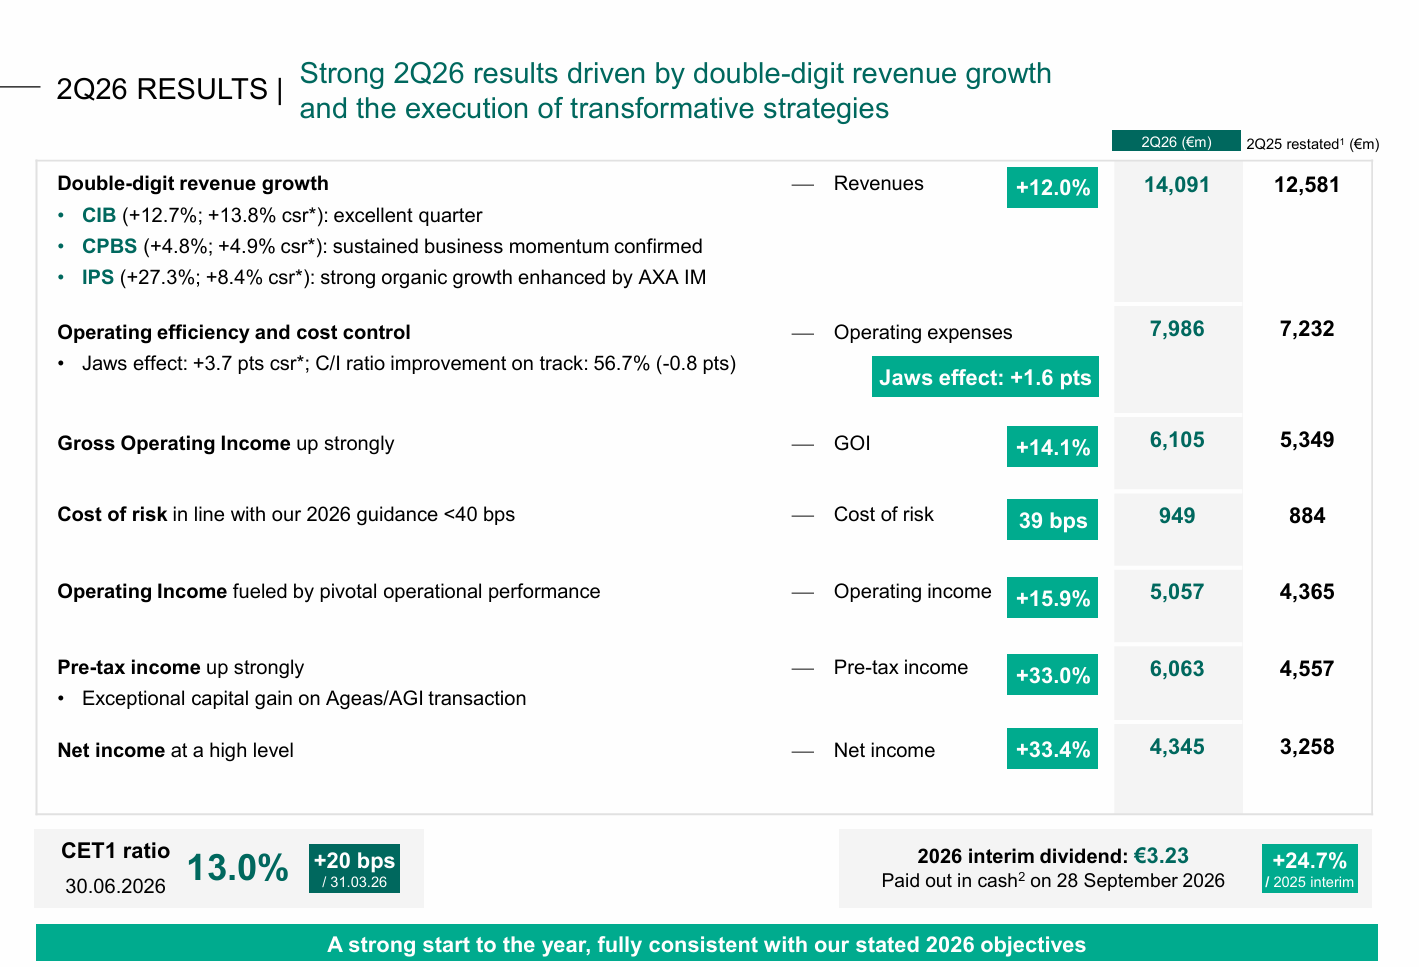
Revenue for the quarter were up 12% YoY (helped by AXA UM acquisition) at 14.1B€ (above analyst estimates of 13.6B€).
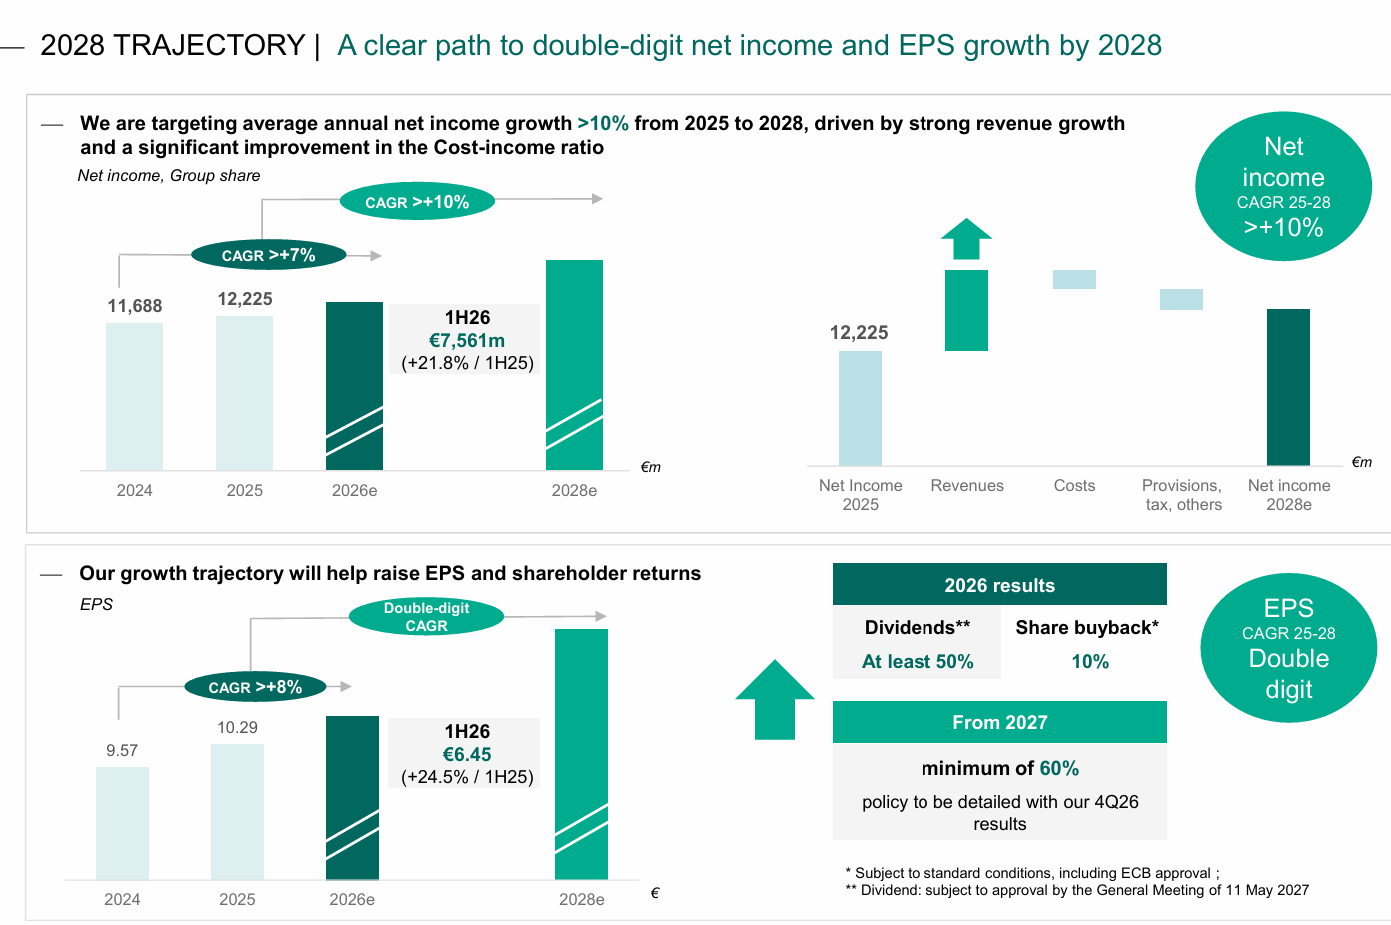
What is notable is that the bank managed to trim its costs, driving operating income growth (+15.9% YoY) ahead of top-line revenue. Looking further ahead, management is targeting 10% annual net income growth through 2028 helped by several initiatives: support function transformation, AI, new integrations and synergies, etc.
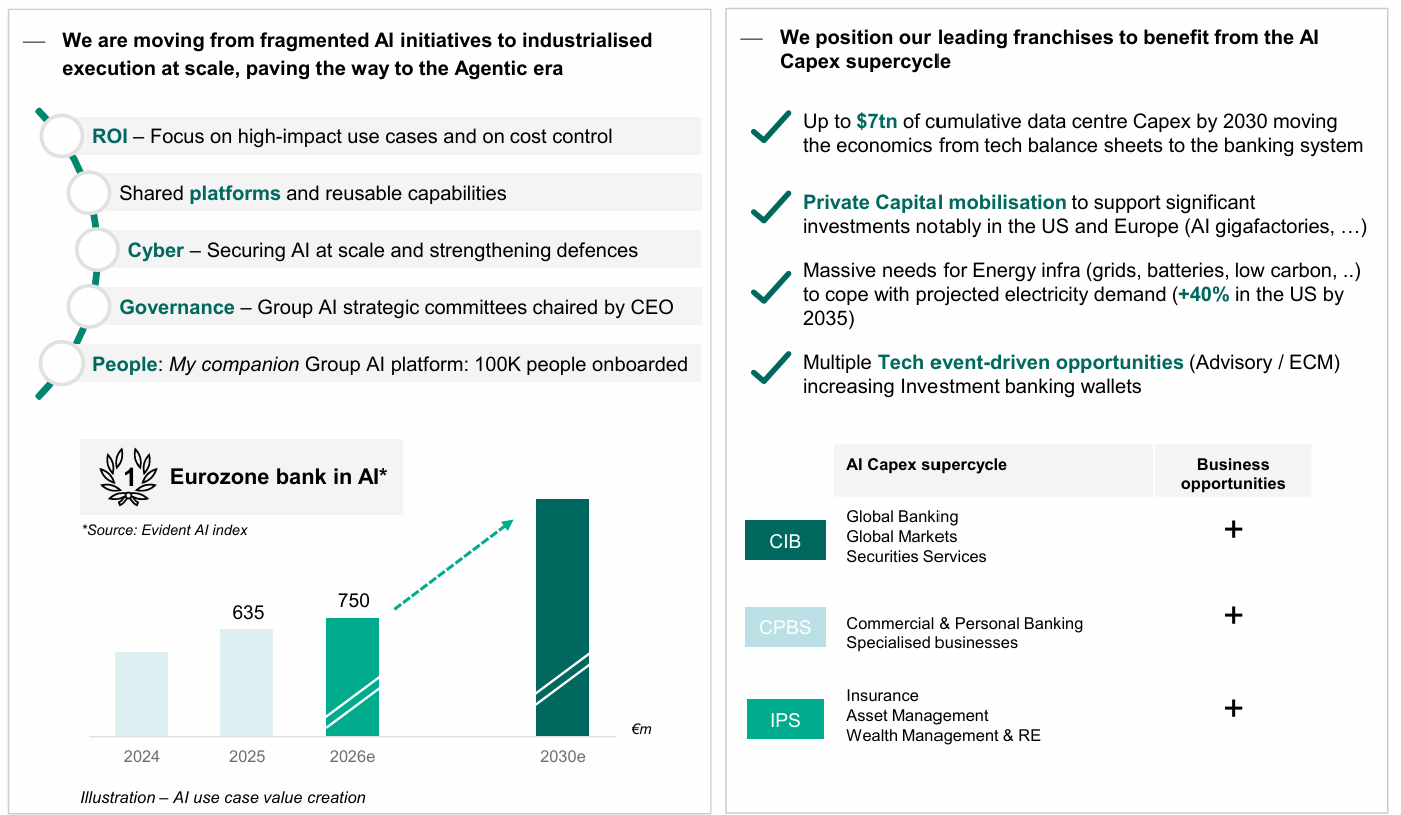
On a lighter note, even a bank can’t resist mentioning AI in its earnings report. But there is a story here: BNP is both deploying AI internally and capturing growth from the broader AI investment cycle.
Recent analyst recommendation updates
July, 15. Deutsche Bank. Hold. 98€ —> 106€
July, 13. JP Morgan. Buy. 106€ —> 110€
July, 09. Goldman Sachs. Buy. 108€ —> 122€
Detailed TSR calculation
The projected Total Shareholder Return (TSR) is built from 6 components, each estimated on an annualized basis:
Organic growth: +4.0%/year. Growth should continue as BNP gains market share
Acquisitions: +1.0%/year. M&A is a strong growth engine for BNP
Dividends: +5.7%/year. This reflects a continuation of the current dividend policy
Share buyback: +2.0%/year. The company deploys a lot of capital for share buyback
Valuation expansion: +0.0%/year. At first glance, BNP Paribas’s sub-10x PE looks low but are roughly in line with a sector structurally capped by low valuations
Margin expansion: +1.2%/year. As the asset base expands, the bank’s cost-to-income ratio should continue to improve
Total: 13.9%/year
My analysis
Banking is traditionally a low-excitement sector. The hurdle with lenders is managing macro cyclicality, as credit and interest rate cycles heavily dictate short-term performance. However, BNP Paribas investment case is positively impacted by 3 clear traits: huge scale (largest bank in Europe), a deep margin of safety in its valuation and highly disciplined M&A.
Combined with accelerating operating leverage, it checks a lot of boxes for an investment. With a strong dividend payload, it can be a foundational asset for income-oriented investors who like the banking sector.
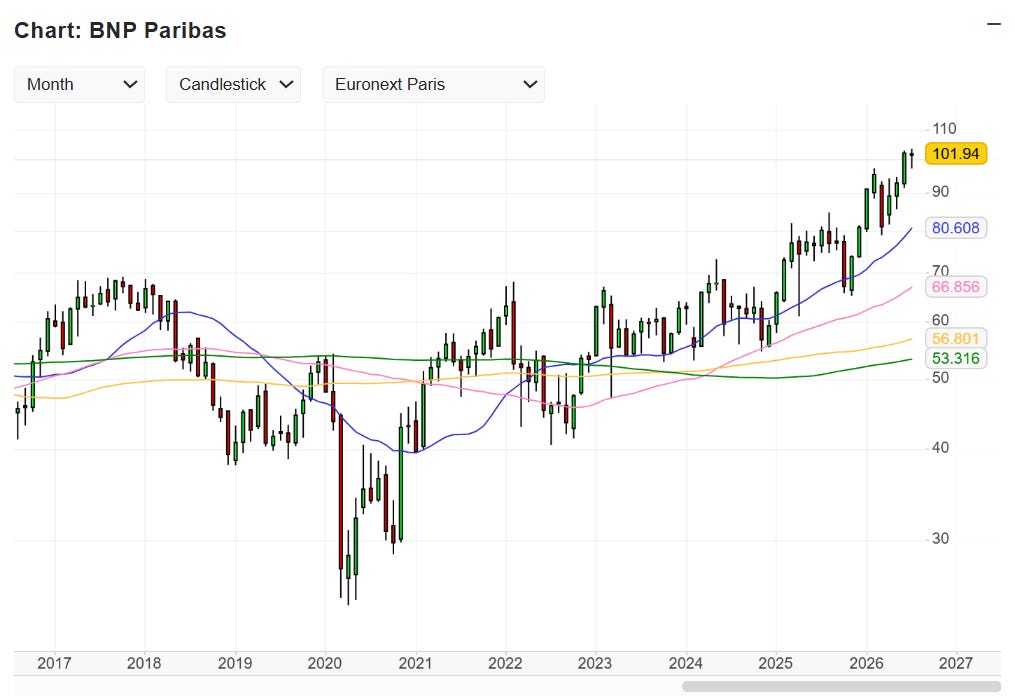
However, because the stock has enjoyed a powerful run (up more than 25% YTD and 80% on a 3-year view) building a position via several entries (across our specific buy zones for instance) and waiting for a consolidation is a a smart way to reduce risk.
The French state steals 1/3 of the dividend and has 3rd highest debt burden of all countries, per capita and per GDP. I don't want to own that bank when the next Euro crisis unfolds.
Great stock!