

Welcome to “Stock of the Week”, a recurring series focused on companies experiencing meaningful news flow or changes in their investment case. The objective is not to react to headlines but to understand what is happening beneath the surface and whether recent developments materially affect the long-term investment thesis.
Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and execution, in order to determine whether the stock is Attractive, Conditional, or Unattractive at the current price. A standardized one-pager accompanies each edition to make the decision process clear and easy to follow.
For paid subscribers, Stock of the Week goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
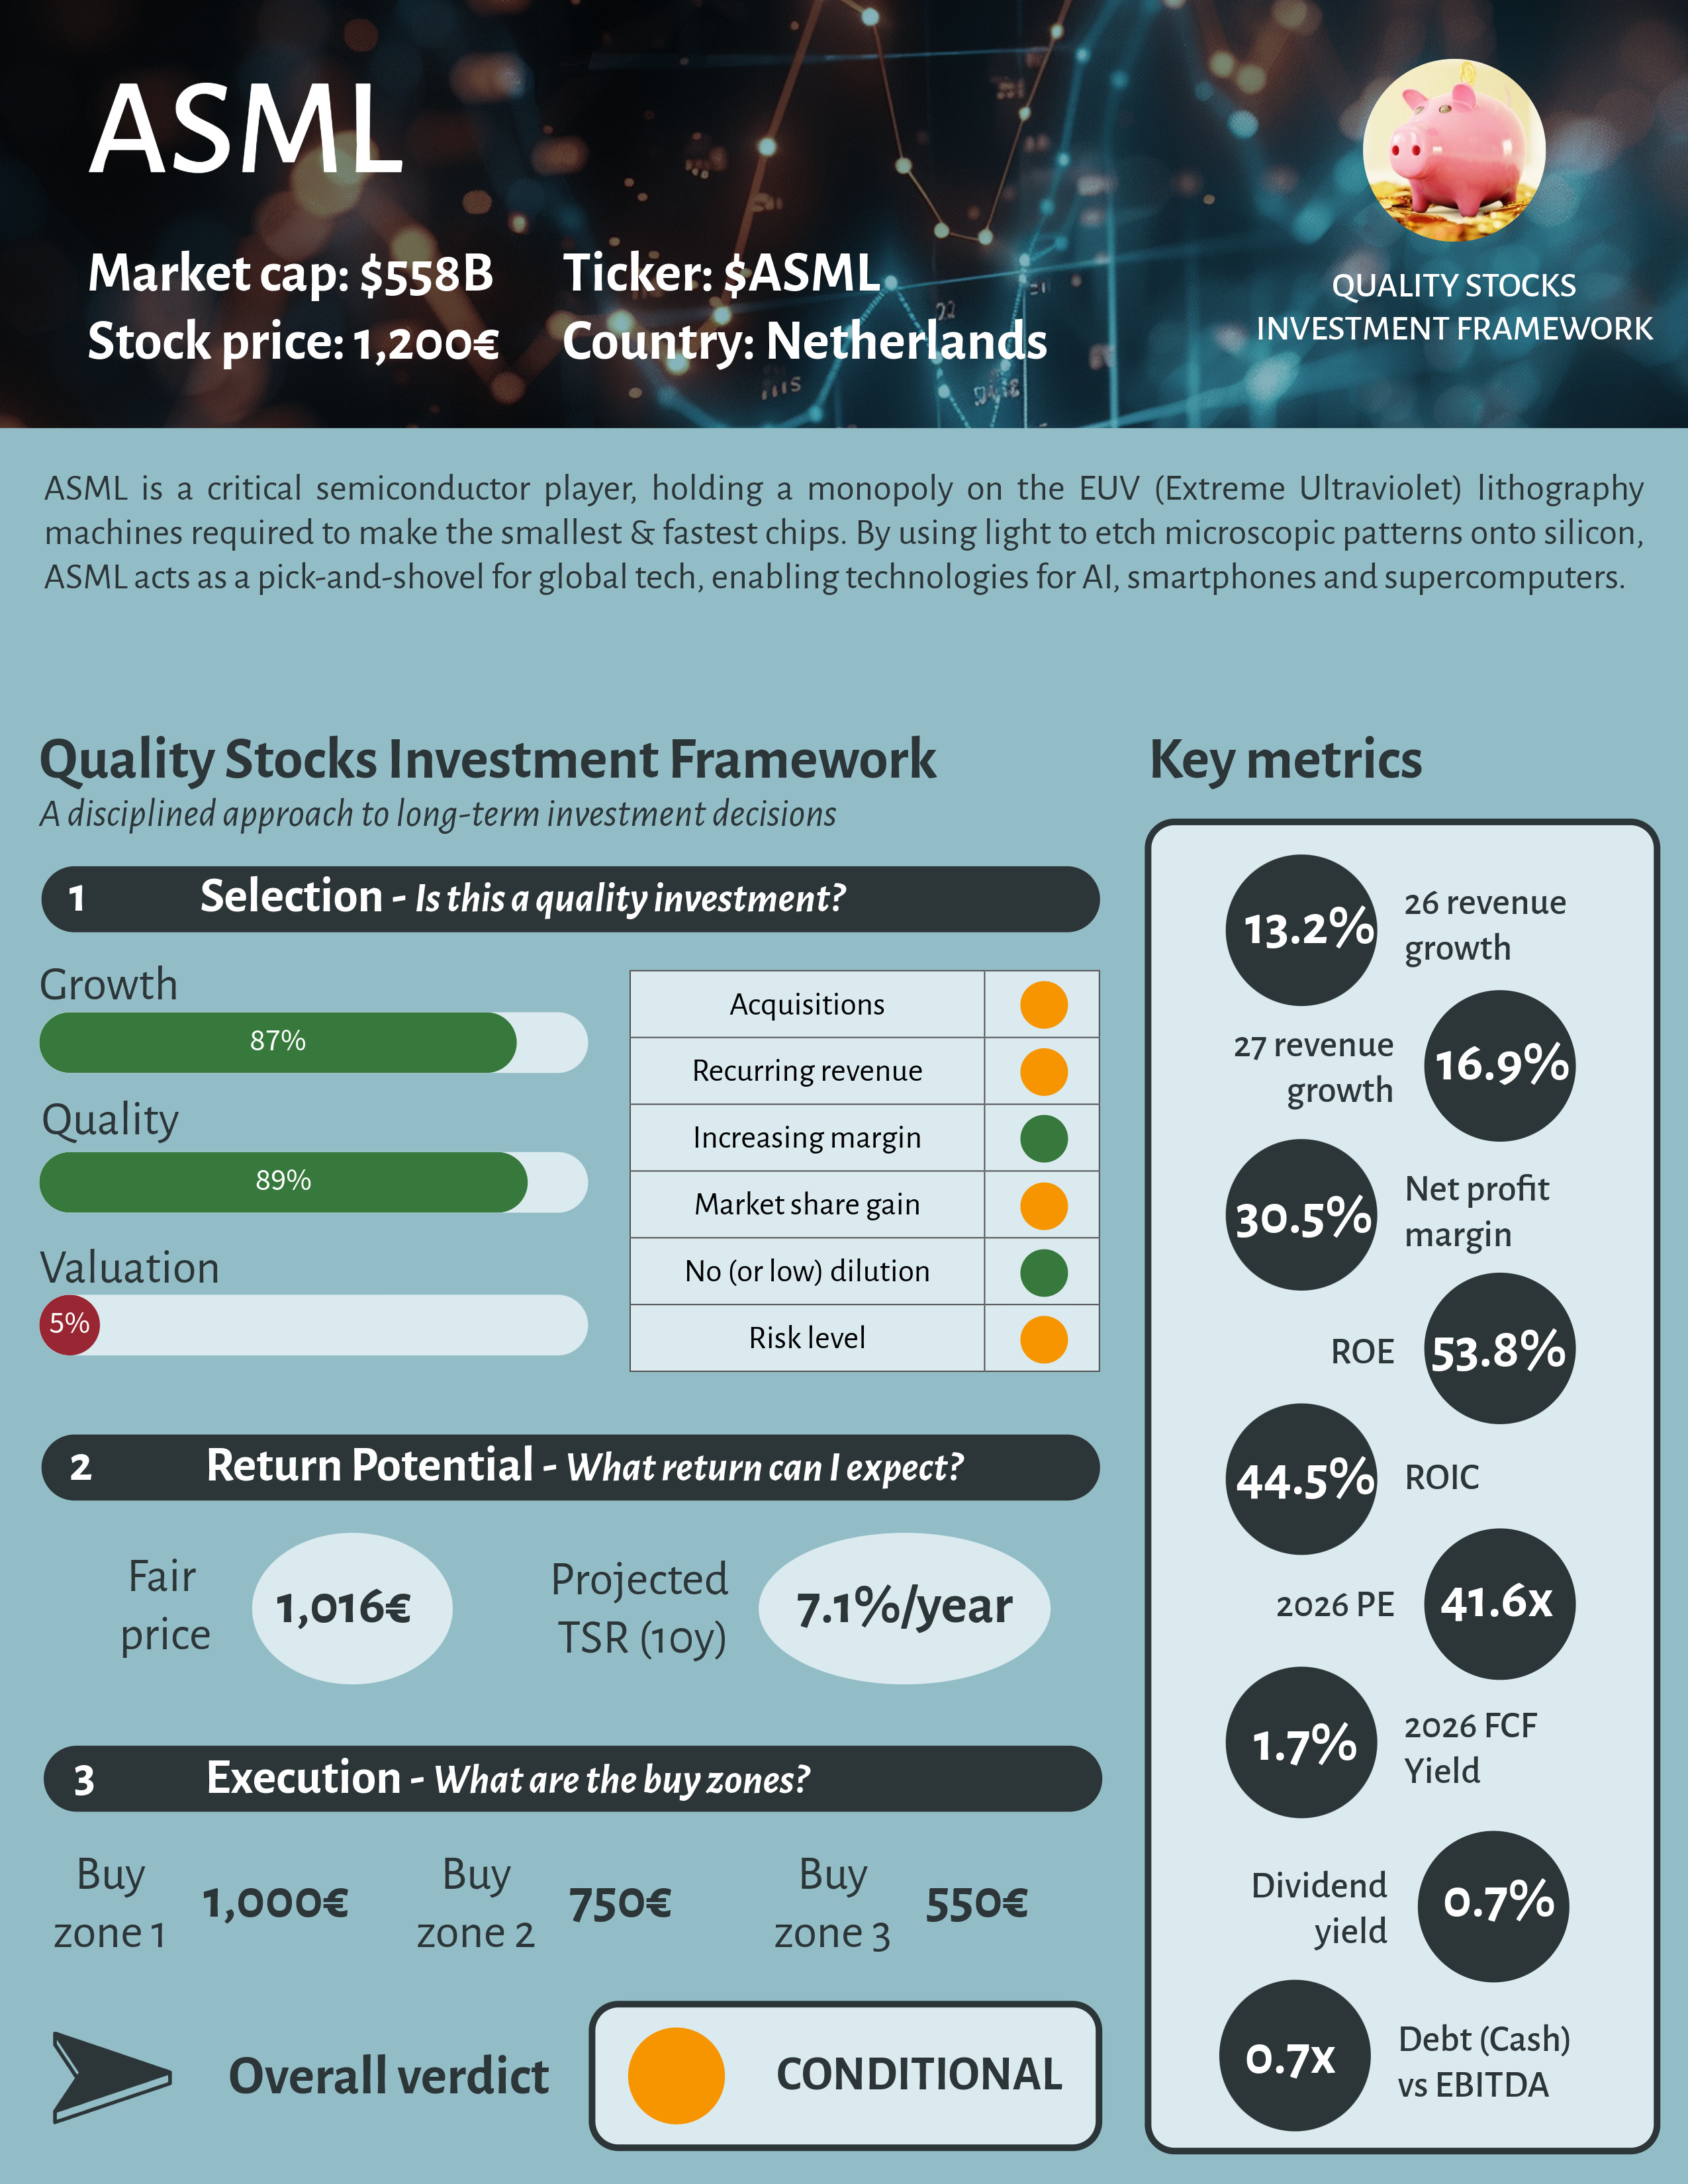
This week’s spotlight is on ASML. The company just silenced the skeptics with a blowout earnings report, headlined by a record-breaking 13.2B in Q4 bookings. This massive surge in orders provides the clear revenue visibility that was missing in previous quarters, effectively reigniting investor optimism. However, with the stock now trading at a significant premium, we have to ask: has the valuation outpaced the fundamentals? Let’s dive into the numbers
Missed an edition? Catch up on our recent forecasts


One Pager
The stock at a glance
Recent news
Total net bookings for the fourth quarter reached a record 13.2B€, nearly doubling the analyst expectations of approximately 7B€ (surpringly low expectations by the way…)
The company ended 2025 with a massive order backlog of 39B€, providing strong revenue visibility for 2026 and 2027
Revenue was officially recognized for the first 2 High-NA EUV systems, signaling that the next generation of chipmaking technology is now moving into the production phase
The CEO highlighted that customers are accelerating their capacity plans due to the sustainability of AI-related demand
China’s share of total net sales is expected to drop to approximately 20% in 2026 (down from over 30% in 2025) due to ongoing export restrictions
ASML announced a new share buyback program of up to 12B€ to be executed by the end of 2028
The company proposed a total 2025 dividend of 7.50€ per share, representing a 17% increase over the previous year
A restructuring plan was introduced to cut approximately 1,700 positions, mainly in management and IT, to focus resources on core engineering and technical innovation
Recent analyst recommendation updates
January, 29. Berenberg. Buy. 1,300€ —> 1,500€
January, 29. Barclays. Buy. 1,200€ —> 1,500€
January, 29. JP Morgan. Buy. 1,300€ —> 1,515€
January, 28. Jefferies. Hold. 1,020€ —> 1,260€
To go beyond the initial assessment, paid subscribers unlock the detailed TSR calculation with underlying assumptions and my analysis of the situation, providing deeper insight into how recent developments affect risks, opportunities and the overall verdict.
