

Welcome to “Stock of the Week”, a recurring series focused on companies experiencing meaningful news flow or changes in their investment case. The objective is not to react to headlines but to understand what is happening beneath the surface and whether recent developments materially affect the long-term investment thesis.
Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and execution, in order to determine whether the stock is Attractive, Conditional, or Unattractive at the current price. A standardized one-pager accompanies each edition to make the decision process clear and easy to follow.
For paid subscribers, Stock of the Week goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
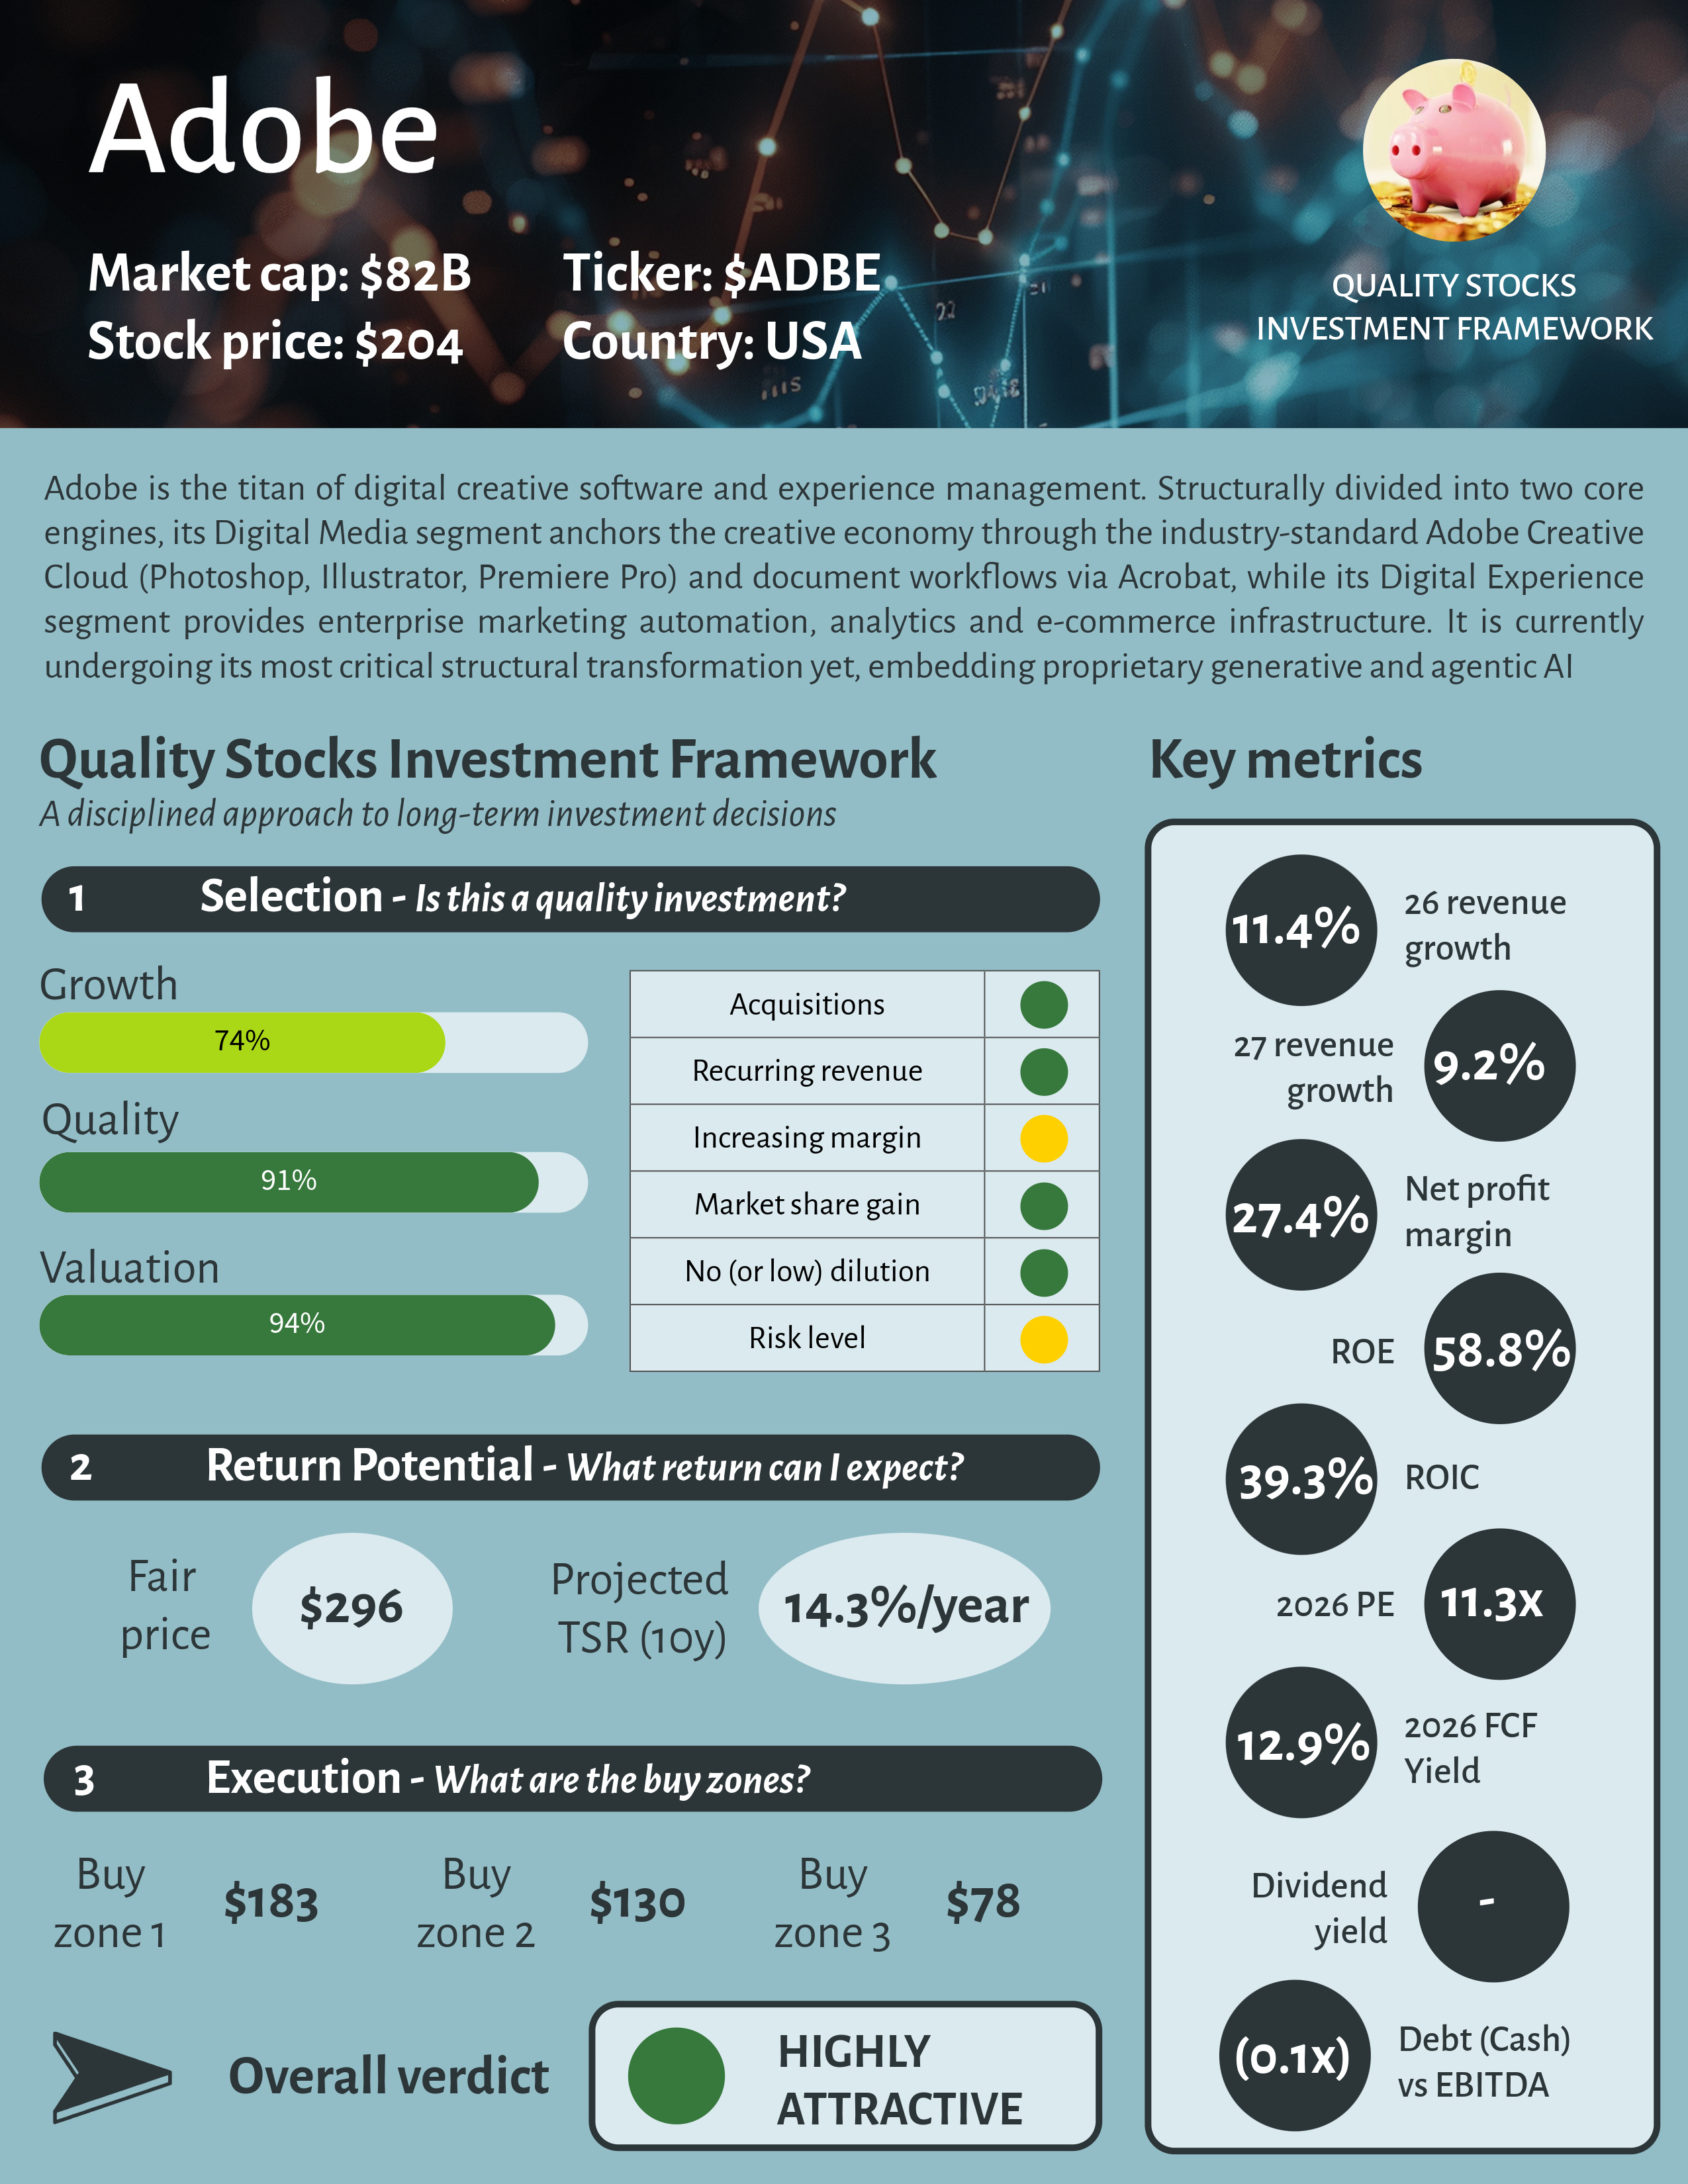
This week’s spotlight is on Adobe. The market has once again proven that it is driven by short-term narrative rather than long-term fundamentals. Following its latest earnings report, Adobe suffered a sharp stock price collapse, despite delivering accelerating growth and a 3x surge in AI-driven revenue. While Wall Street treats this price pressure as proof that the business is under threat, the underlying metrics tell a completely different story. Let’s dive in.
Missed an edition? Catch up on our recent analyses


One Pager
The stock at a glance
Want to understand how the Quality Stocks Investment Framework works? This article breaks it down for you

Data for this week’s analysis was sourced via MarketScreener. It is my go-to platform for global stock data and analyst price targets. If you are looking to upgrade your research toolkit, click here (Full disclosure: this is an affiliate link, so you will be supporting this newsletter at no extra cost to you!)
Recent news
Adobe delivered record second-quarter revenue of $6.62B, marking an 11% YoY growth in constant currency that outperformed Wall Street consensus
Management raised its FY financial outlook, projecting total fiscal revenue between $26.50B and $26.60B alongside adjusted EPS of $24.35 to $24.45
Annualized recurring revenue from AI-first products tripled YoY to surpass a $500M run-rate, driven by strong adoption of Firefly and Acrobat AI Assistant
Top-of-funnel traffic to Adobe.com surged 35% YoY, helping push total monthly active users across Acrobat and Express past 850M
Chief Financial Officer Dan Durn announced his sudden departure to take the top financial seat at Marvell Technology, with long-time corporate finance veteran Steve Day stepping in as interim CFO
The sudden CFO vacancy introduces execution risk as the board is already conducting a comprehensive search to replace long-serving CEO Shantanu Narayen, who announced his intention to step down earlier this year
Management explicitly confirmed an aggressive pivot toward free user journeys, choosing to defer planned Creative Cloud price increases in order to maximize market share (creating fears among investors that Adobe’s pricing power is gone due to AI)
Executives acknowledged that prioritizing friction-free user acquisition over immediate monetization will temporarily pressure individual net new annualized recurring revenue in the second half of the year
The company successfully integrated its recent $480M annualized recurring revenue acquisition of Semrush into its reporting base
Adobe capitalized on recent market volatility by aggressively repurchasing approximately 8.5M shares during the quarter (around 2% of the total share outstanding) under its newly authorized $25B buyback program
Recent analyst recommendation updates
June, 12. Griffin Securities. Buy. $405 —> $380
June, 12. UBS. Hold. $260 —> $225
June, 12. Jefferies. Hold. $290 —> $230
June, 12. RBC. Buy. $350 —> $285
June, 12. Stifel. Buy —> Hold. $350 —> $200
To go beyond the initial assessment, paid subscribers unlock the detailed TSR calculation with underlying assumptions and my analysis of the situation, providing deeper insight into how recent developments affect risks, opportunities and the overall verdict
