

Microsoft recently delivered a classic “double beat” exceeding expectations on both revenue and earnings. Azure is still growing at 39%. Yet the stock was met with a swift 10% sell-off. While the headline numbers suggest business as usual, a deeper look reveals a significant shift in how Wall Street values Big Tech. The analysts are divided, but we may enter a new reality: the AI honeymoon phase is over. Results are needed.
In this article, we will peel back the layers of the earnings report to uncover the negative spots hidden beneath the growth metrics. From a record-breaking $37.5B CAPEX bill to a sudden transparency regarding OpenAI exposure, we will explore why the market is suddenly demanding more than just a beat, it is demanding a clearer path to ROI.
Beyond the earnings, we analyze a deeper trend: a fundamental change in the market's risk appetite. We will discuss why this new stance from analysts might be the opening chapter of a major sector-wide correction.
Earnings report summary
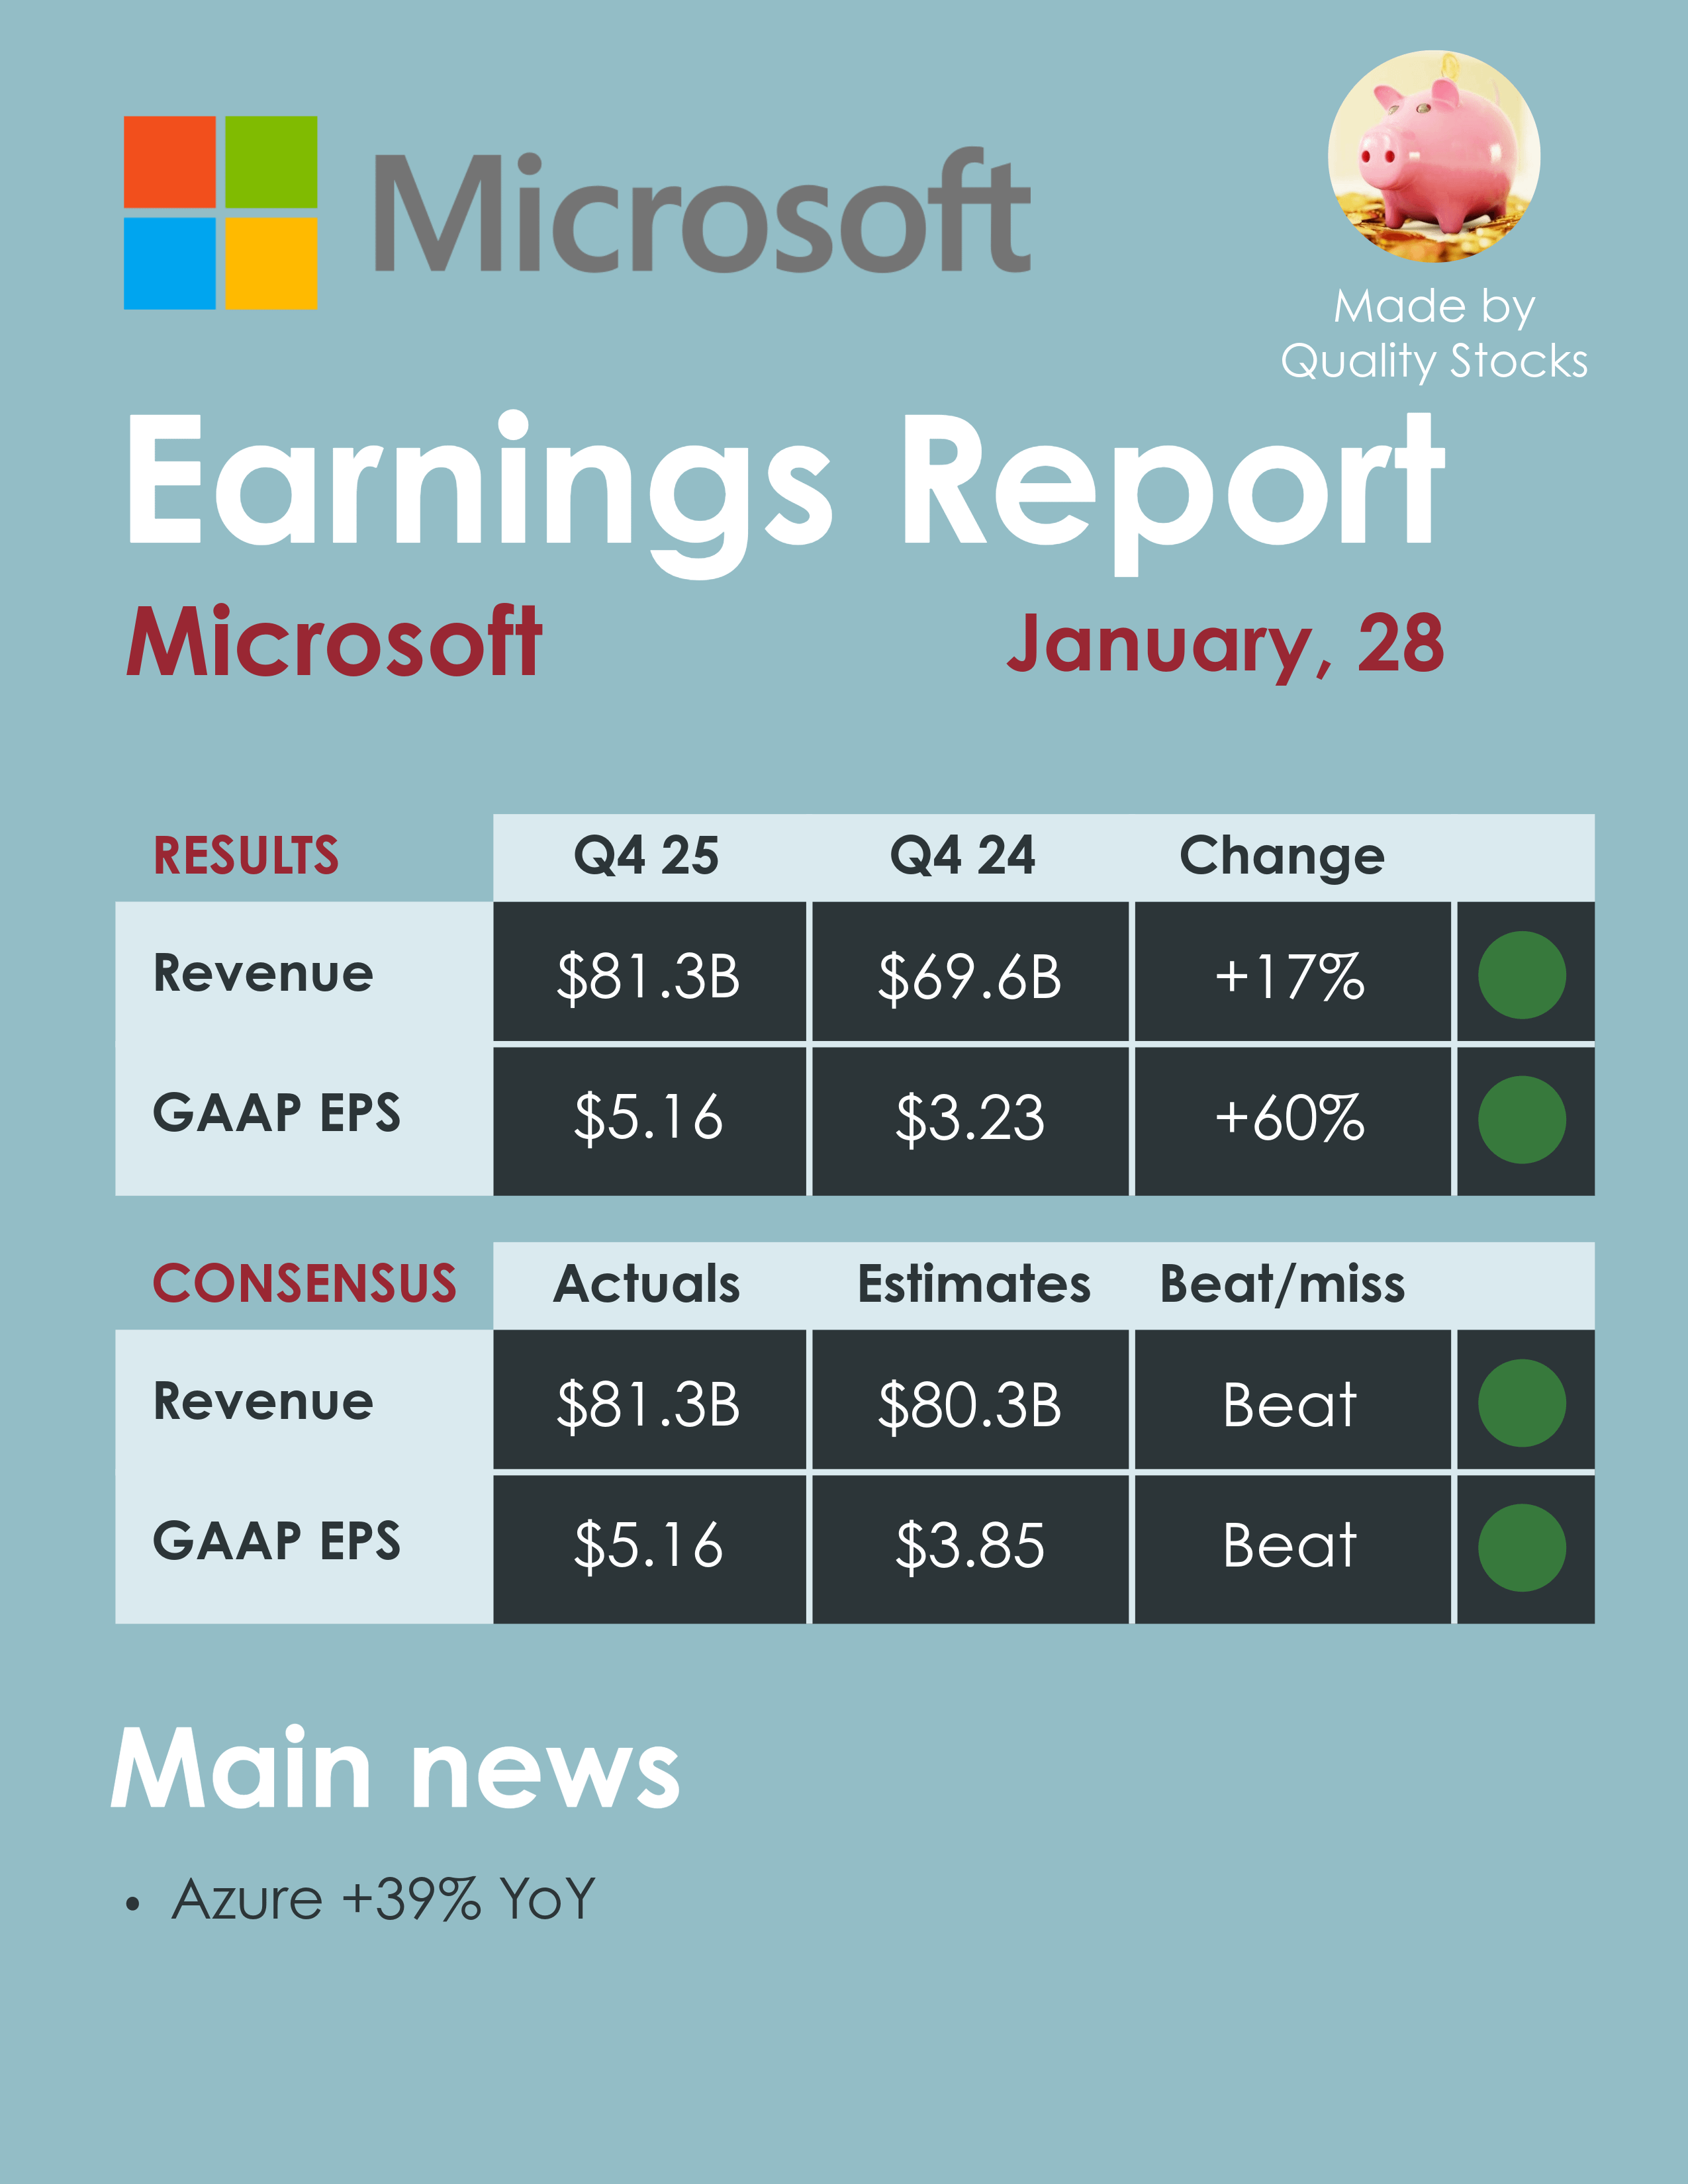
Microsoft delivered a powerhouse performance for its fiscal Q2 2026, surpassing Wall Street’s expectations on nearly every major metric. Revenue reached a record $81.3B (+17% YoY) while adjusted EPS hit $4.14, handily beating the $3.93 consensus.
The Intelligent Cloud segment remained the primary engine of this growth, with Microsoft Cloud revenue crossing the historic $50B milestone for a single quarter. Azure specifically grew 39% (38% in constant currency), proving that the appetite for AI infrastructure and enterprise cloud services remains robust.
The darker side of the results
In the following sections, I will break down the specific catalysts that spooked the market. However, my analysis leads to a different conclusion than the current consensus. After we examine the red flags through the market's lens, I will present my view.
1. The artificial GAAP EPS boost
Impact: ⭐️ (low)
A major point of confusion in this report is the massive gap between Microsoft’s reported GAAP earnings and its operational reality. On a GAAP basis, diluted EPS skyrocketed 60% to $5.16, but this figure was heavily inflated by a net gain related to investments in OpenAI.
When you strip away these non-cash accounting gains to look at the actual business performance (Non-GAAP), the EPS drops to $4.14. While a $4.14 result is still a beat, the market realized that the headline growth was fueled by paper gains rather than purely by the company’s activities.
2. The surge in CAPEX
Impact: ⭐️⭐️⭐️ (high)
The most glaring concern was the massive jump in capital spending, which reached a record $37.5B for the quarter, a 66% increase YoY. Investors are beginning to push back against this blank check approach to AI infrastructure, fearing that the bill for data centers and chips is growing much faster than the actual profits they produce. This surge in spending has directly pressured free cash flow, leading to a timing mismatch where the costs are immediate, but the financial rewards remain years away.
3. The OpenAI concentration risk
Impact: ⭐️⭐️ (medium)
For the first time, Microsoft revealed the scale of its dependency on a single partner, disclosing that 45% of its $625B commercial backlog (approximately $280B) is tied specifically to OpenAI. This created a concentration risk alarm for Wall Street: if OpenAI faces a slowdown (due to competition or slower than expected adoption), regulatory hurdles or financial instability, nearly half of Microsoft’s future growth projections could vanish. Analysts pointed out that when you strip away the OpenAI contracts, the organic backlog growth was a much more modest (28%).
4. Azure’s disappointing growth
Impact: ⭐️⭐️ (medium)
While a 39% growth rate would be a triumph for almost any other company, analysts expected more. History appears to be repeating itself. For those with a long memory, this mirrors the 2022 sell-off when analysts punished the stock for a mere 1% miss on Azure growth expectations. The market was positioned for an acceleration above 40%. Instead, Azure’s performance suggests that Microsoft is hitting a temporary growth ceiling. Management attributed this to capacity constraints, essentially admitting they cannot build data centers fast enough to meet demand.
My analysis
While the market’s reaction was swift and severe, I believe we are seeing a classic case of short-term overreaction fueled by profit-taking. Microsoft’s valuation, while certainly not cheap, was far from irrational given its dominant position and growth outlook. However, as we saw in 2022, the market treats any Microsoft miss (even a 1% deviation) as a catalyst to derisk.
In my view, this -10% move says less about Microsoft’s fundamental health and more about a market that was looking for any excuse to rotate out of high-flying tech. We are currently witnessing a significant market rotation. While headlines focus on the tech giants, defensive sectors like healthcare and utilities are quietly outperforming.
This volatility may be the first signal of a deeper shift in the market’s psychological state. Historically, the stock market is a discounting mechanism that anticipates the next phase 6 to 9 months in advance. The aggressive punishment of a double beat may suggest that investors are silently bracing for a transition, perhaps preparing for the next bear market.
If the market is indeed shifting its stance, the focus will move from growth at any cost, to capital preservation, margins and recession-proofing. Microsoft is not failing, rather it is the canary in the coal mine for a market that is fundamentally rethinking its appetite for risk as we move further into 2026.
