

Welcome to “Stock Analysis”, a new series where we go beyond headlines to understand how businesses really make money. The series focuses on introducing new investment ideas by highlighting often less-followed companies. Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and identify buy zones, providing readers with the tools and context needed to form their own investment decisions.
For paid subscribers, each Stock Analysis goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
Explicit bull and bear cases. It helps frame both upside potential and downside risks, making uncertainties visible rather than implicit and supporting more balanced, risk-aware decisions
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
For this 7th episode, it is time to analyze AJ Bell. Following a stellar earnings report, the stock surged 25% in a single week, officially doubling from my initial entry price. As one of the first additions to my small-cap portfolio, its value was clear to me from the start. Now is the perfect time to look under the hood and analyze why this under-the-radar business model continues to outperform.
Previous stock analyses


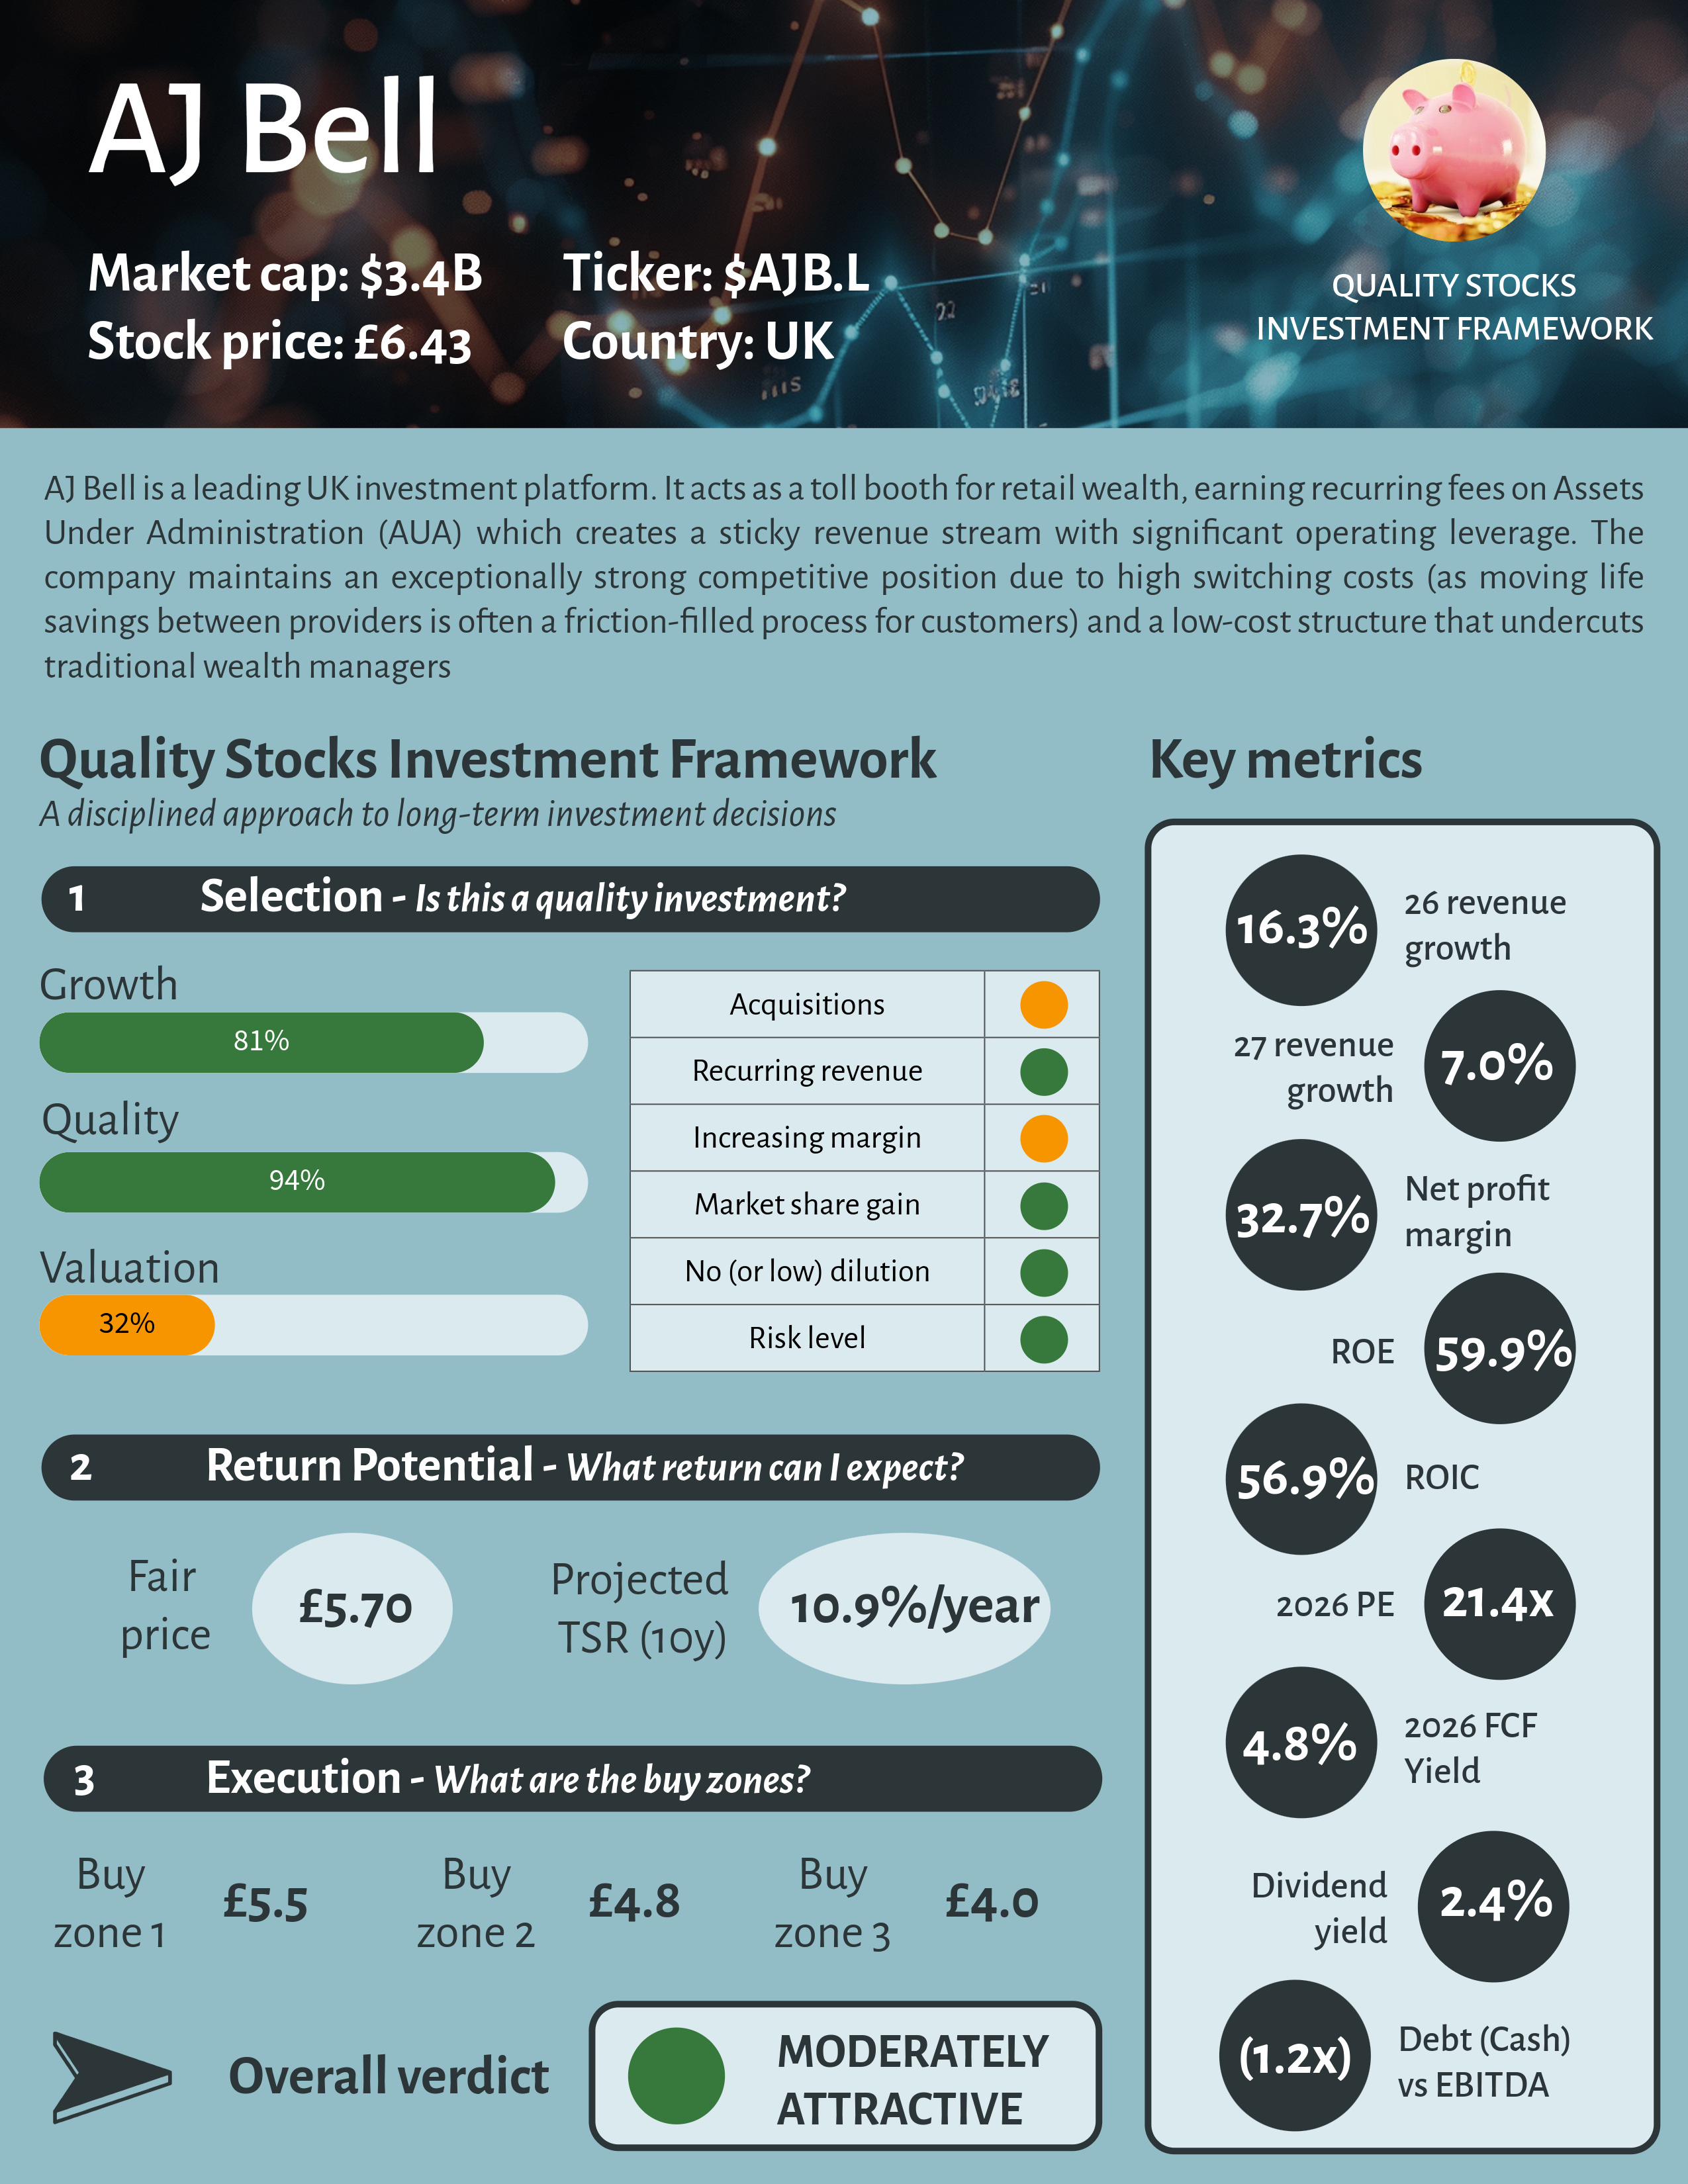
One Pager
The stock at a glance
The business model
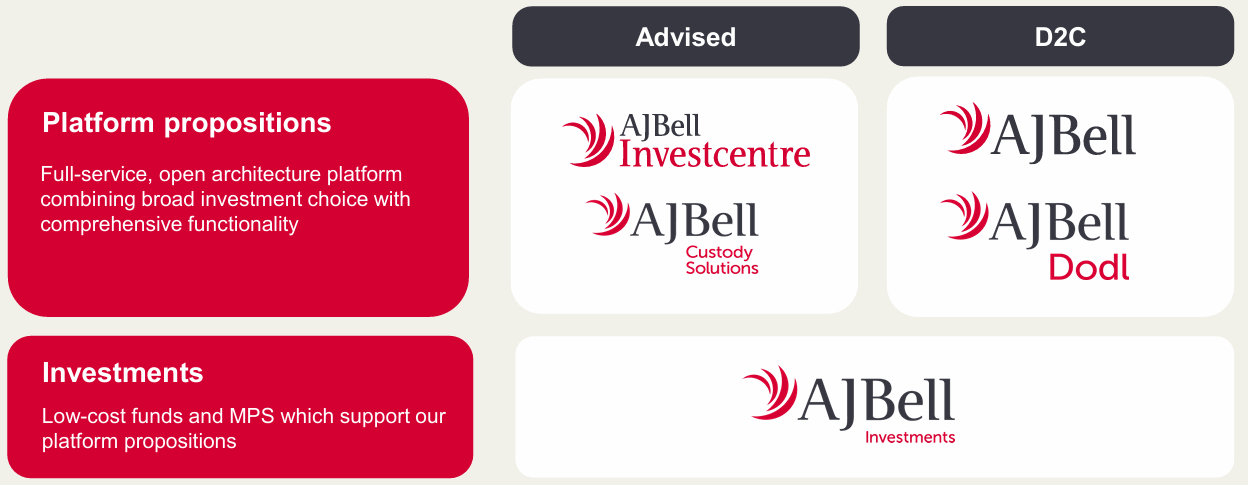
AJ Bell operates a dual-channel investment platform that serves both DIY retail investors (D2C) and financial advisers (Advised). At its core, the business acts as a digital toll booth for the UK wealth market by providing the infrastructure (the technology, custody and administration). It earns recurring fees based on the total Assets Under Administration (AUA). This revenue model means that as the markets rise or customers contribute more savings, AJ Bell’s revenue grows without a linear increase in its cost base.
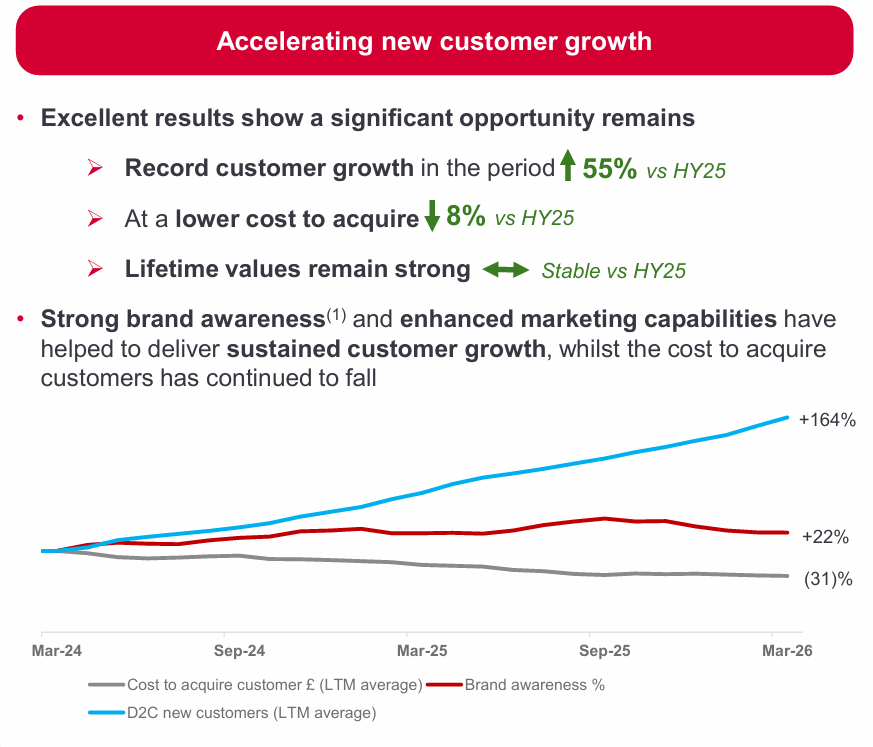
The brilliance of the model lies in its operating leverage and capital-light nature. Because the platform is built on a hybrid technology stack, adding a new customer costs very little once the initial fixed costs are covered. In the first half of 2026, the company demonstrated this by reporting a 19% surge in revenue to £183M. This scalability allows the company to reinvest in brand marketing (which drove a record 79,000 new customers in early 2026) while simultaneously returning significant cash to shareholders through dividends and buybacks.
Furthermore, AJ Bell benefits from sticky, high-switching-cost relationships. Moving a lifetime of pension and ISA savings to a competitor is a friction-heavy process, leading to low churn. This creates a predictable float of assets that also generates interest income on cash balances, a secondary revenue stream that has become particularly lucrative in the current interest rate environment. By focusing on a low-cost, user-friendly experience, AJ Bell has positioned itself as a structural winner in the UK’s shift toward self-directed retirement planning.
The outlook
The long-term outlook for AJ Bell is centered on its role as a primary beneficiary of the structural platformification of UK wealth. Despite its recent growth, the company still only commands around 5% of a total addressable market estimated at over £2.4T. As legacy, high-cost paper-based providers become obsolete, AJ Bell acts as a vacuum for these assets. Their expansion strategy is built on capturing the full value chain; by growing their in-house investment arm (AJ Bell Investments), they are successfully migrating customers from being platform users to being investment clients, effectively doubling their fee opportunity on the same pound of assets.
Furthermore, the strategy has shifted from pure customer acquisition to a focus on technological dominance. The company is leaning into automation and AI-driven service models. Finally, the regulatory environment in the UK continues to act as a tailwind. As the government encourages individual retirement responsibility, the platform becomes an essential utility for the middle and upper-class saver.
To go beyond the initial analysis, paid subscribers unlock the detailed TSR calculation with underlying assumptions, explicit bull and bear cases and my full analysis beyond the verdict, providing deeper insight into risks, opportunities and the investment decision process
