

Welcome to “Stock Analysis”, a new series where we go beyond headlines to understand how businesses really make money. The series focuses on introducing new investment ideas by highlighting often less-followed companies. Each article applies the Quality Stocks Investment Framework to assess business quality, return potential and identify buy zones, providing readers with the tools and context needed to form their own investment decisions.
For paid subscribers, each Stock Analysis goes a step further by opening up the full reasoning behind the investment thesis and decision process:
Detailed TSR calculations, including all underlying assumptions. This allows investors to understand what must go right for the investment to deliver acceptable returns and to stress-test their own expectations against explicit inputs
Explicit bull and bear cases. It helps frame both upside potential and downside risks, making uncertainties visible rather than implicit and supporting more balanced, risk-aware decisions
My analysis beyond the overall verdict. This provides a deeper insight, enabling investors to form an independent view rather than relying solely on a conclusion
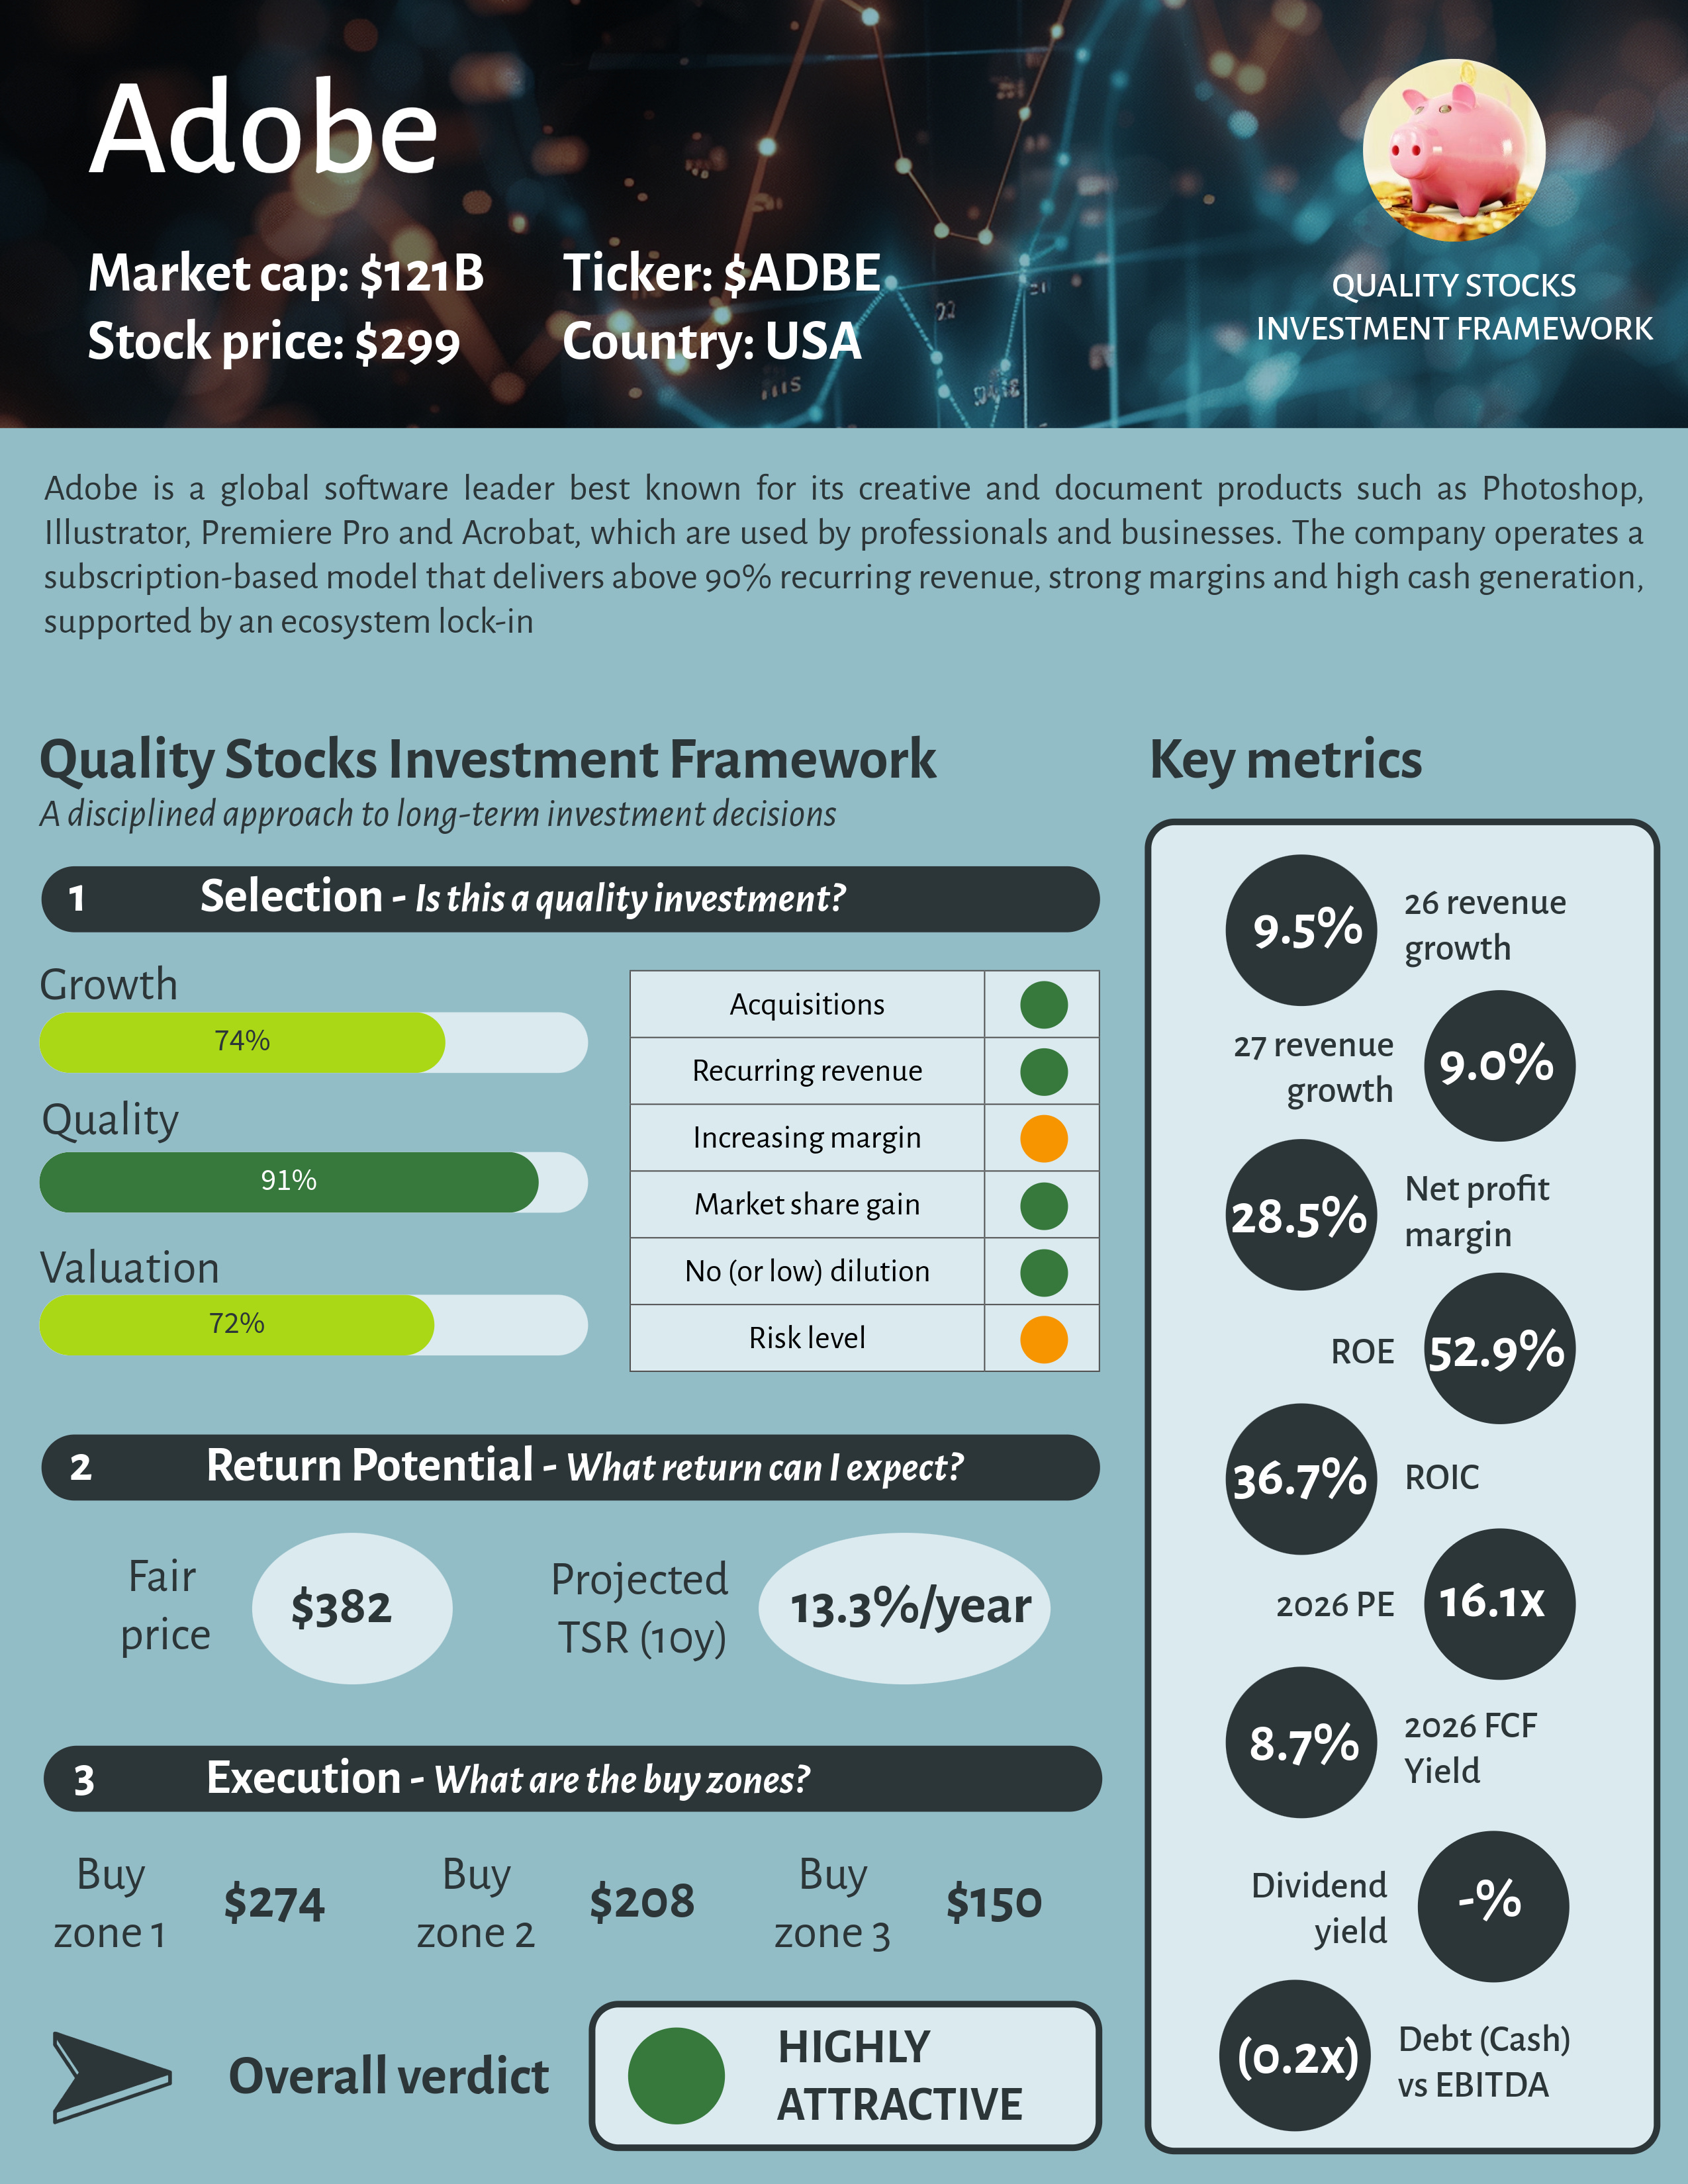
For this 3rd episode, it is time to analyze Adobe. The company has been drawing significant attention recently, with 2 camps of investors emerging: those who fear that AI could disrupt Adobe’s business and those who believe the company is well positioned to monetize AI. With a PE of 16x, valuation is close to all-time low. Let’s dive in.
Previous stock analyses


One Pager
The stock at a glance
The business model
Adobe organizes its business into 3 core revenue segments that reflect how it sells products and services to customer:
Digital Media. This is Adobe’s largest segment (3/4 of sales) and includes subscription revenue from products focused on creative work and document workflows. Creative Cloud: Core creative tools such as Photoshop, Illustrator, Premiere Pro, Lightroom and Adobe Express. Document Cloud: PDF, e-signatures, Acrobat and workflow tools for creating, editing, sharing and signing documents. This segment generates the majority of Adobe’s revenue
Digital Experience (Experience Cloud). This segment focuses on enterprise customers. It includes tools that help businesses manage customer experiences, personalization, analytics, content and digital marketing at scale. Products include Adobe Experience Manager (AEM), Adobe Analytics or Adobe Target
Publishing and Advertising. Historically smaller, this segment includes legacy products and services oriented toward publishing workflows, advertising technology and certain specialized tools
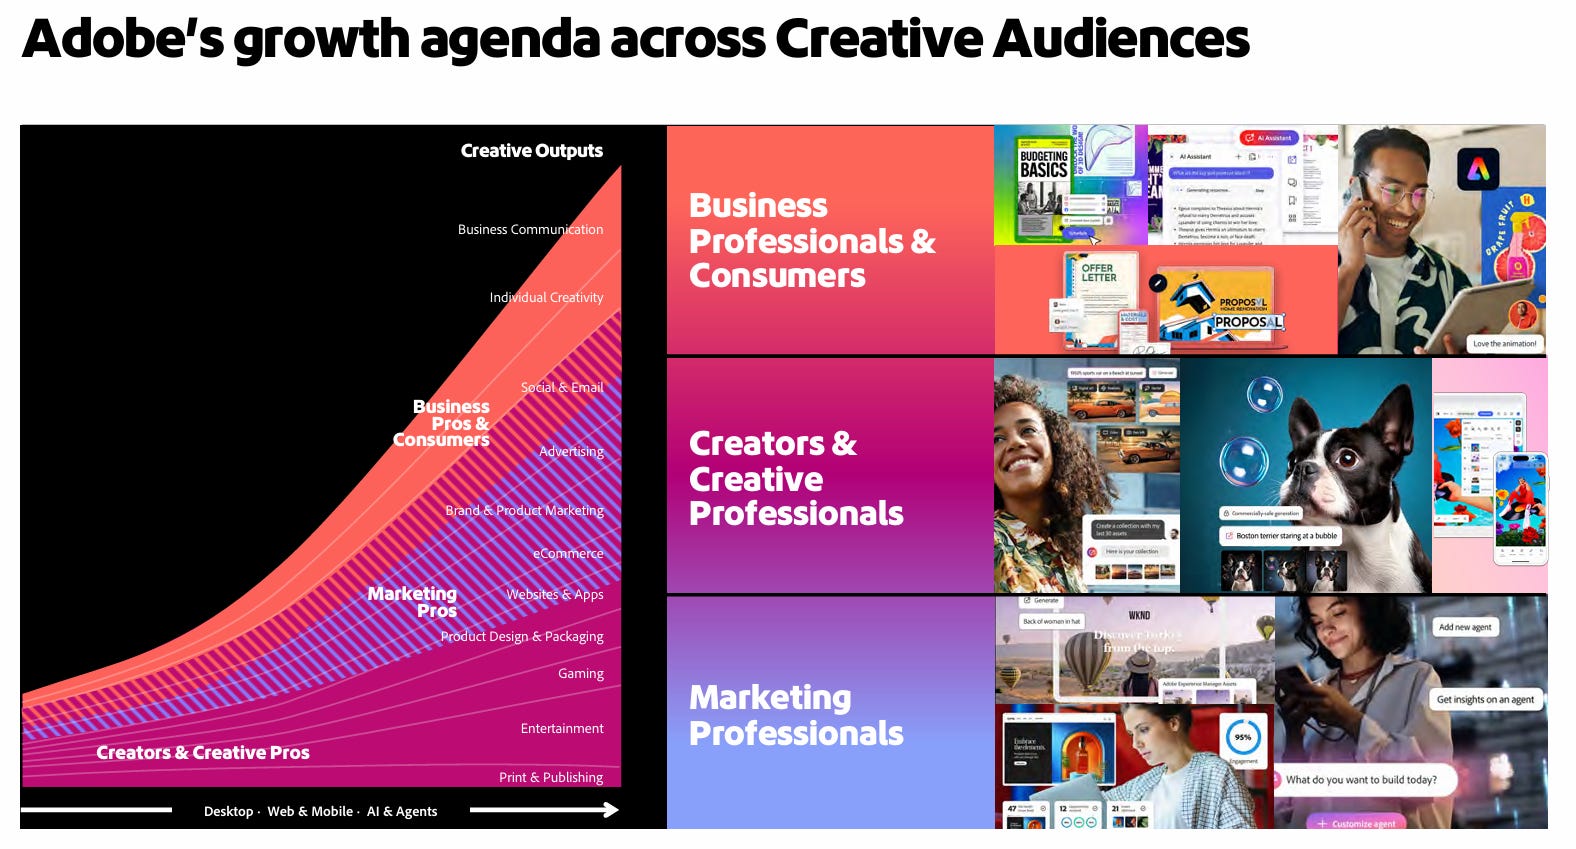
This slide clearly shows the 3 main audiences of the company: business professionals & consumers, creators & creative professionals and market professionals.
Adobe and AI
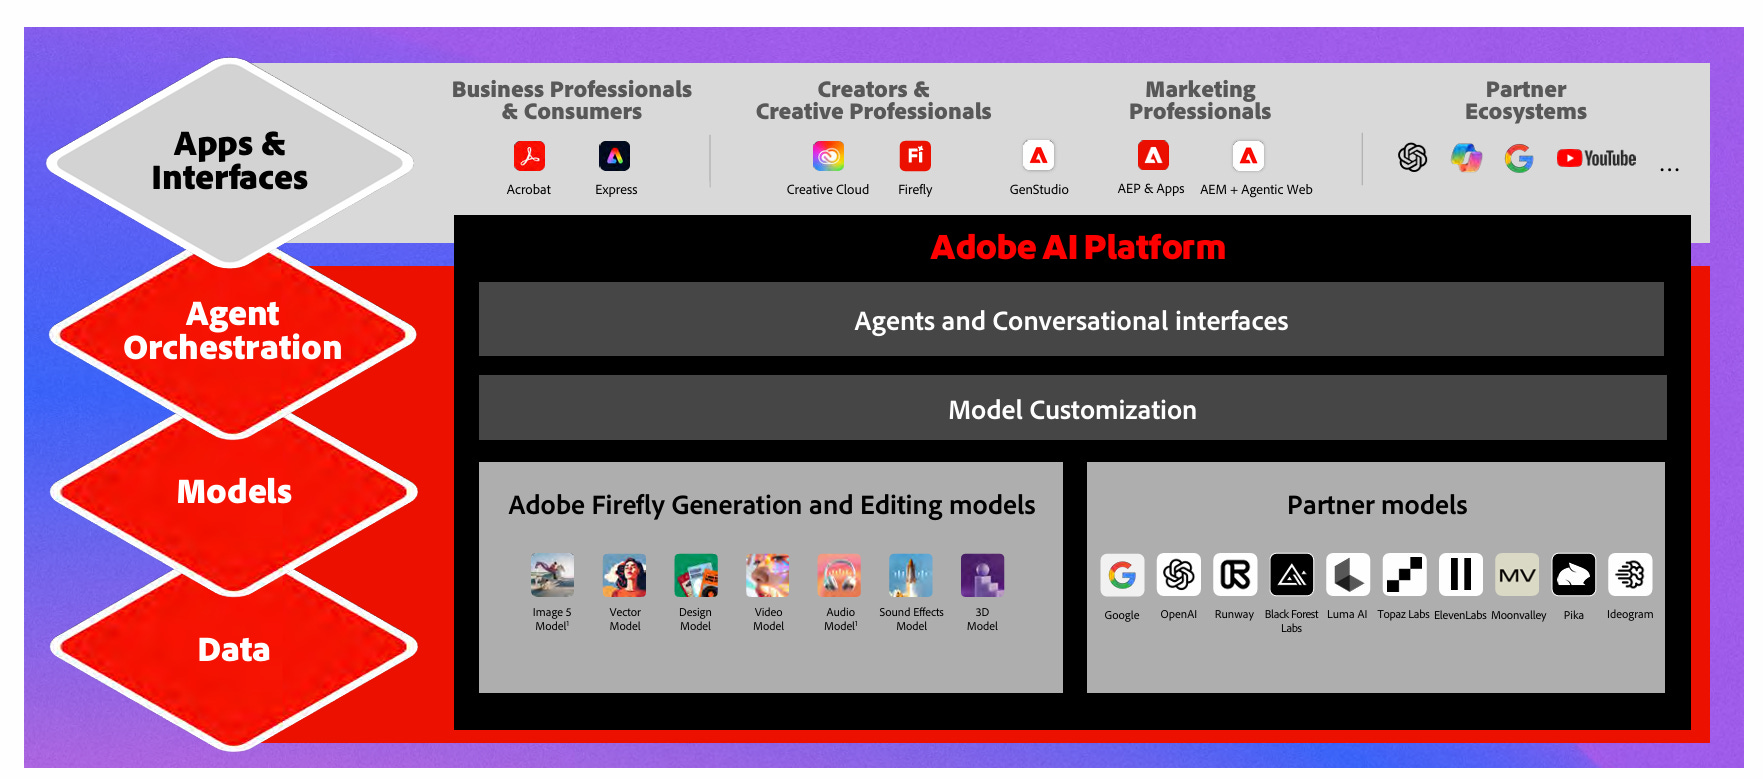
Adobe’s AI strategy is built as a full-stack platform that embeds AI directly into its core products, from Creative Cloud and Firefly to Acrobat and Experience Cloud. Adobe combines its own Firefly generation and editing models with partner models, layers them with agent-based and conversational interfaces and grounds everything in structured data. This is the long-term vision but execution is still ongoing and the platform continues to evolve (and improve).
This strategy is highly relevant for AI monetization because Adobe can charge for AI as productivity and workflow value, not just usage. AI features drive higher subscription tiers, add-on pricing and increased seat adoption, while enterprise customers are willing to pay for integrated AI at scale.
AI does increase competitive risk for Adobe. On the risk side, generative AI dramatically lowers the barrier to entry for creative tools. New players can build fast, cheap, AI-first products for specific use cases (images, video, social content) without decades of development. This puts pressure on Adobe at the low end of the market, especially among casual users and small creators who may accept basic and simpler outputs and switch more easily.
However, Adobe’s defensive position is strong. Professional creators, enterprises and marketing teams rely on specific and deep functionality and workflow integration. Adobe is also an ecosystem with collaboration tools so switching costs remain.
Higher productivity could reduce the number of seats over time, but this should be offset by AI monetization through usage-based or credit (ticket) systems, ultimately lifting revenue per seat. As a result, I do not view AI as the threat the market currently seems to fear. That said, as always, it remains important to stay cautious and monitor concrete signals that could indicate a genuine shift in risk.
To go beyond the initial analysis, paid subscribers unlock the detailed TSR calculation with underlying assumptions, explicit bull and bear cases and my full analysis beyond the verdict, providing deeper insight into risks, opportunities and the investment decision process
